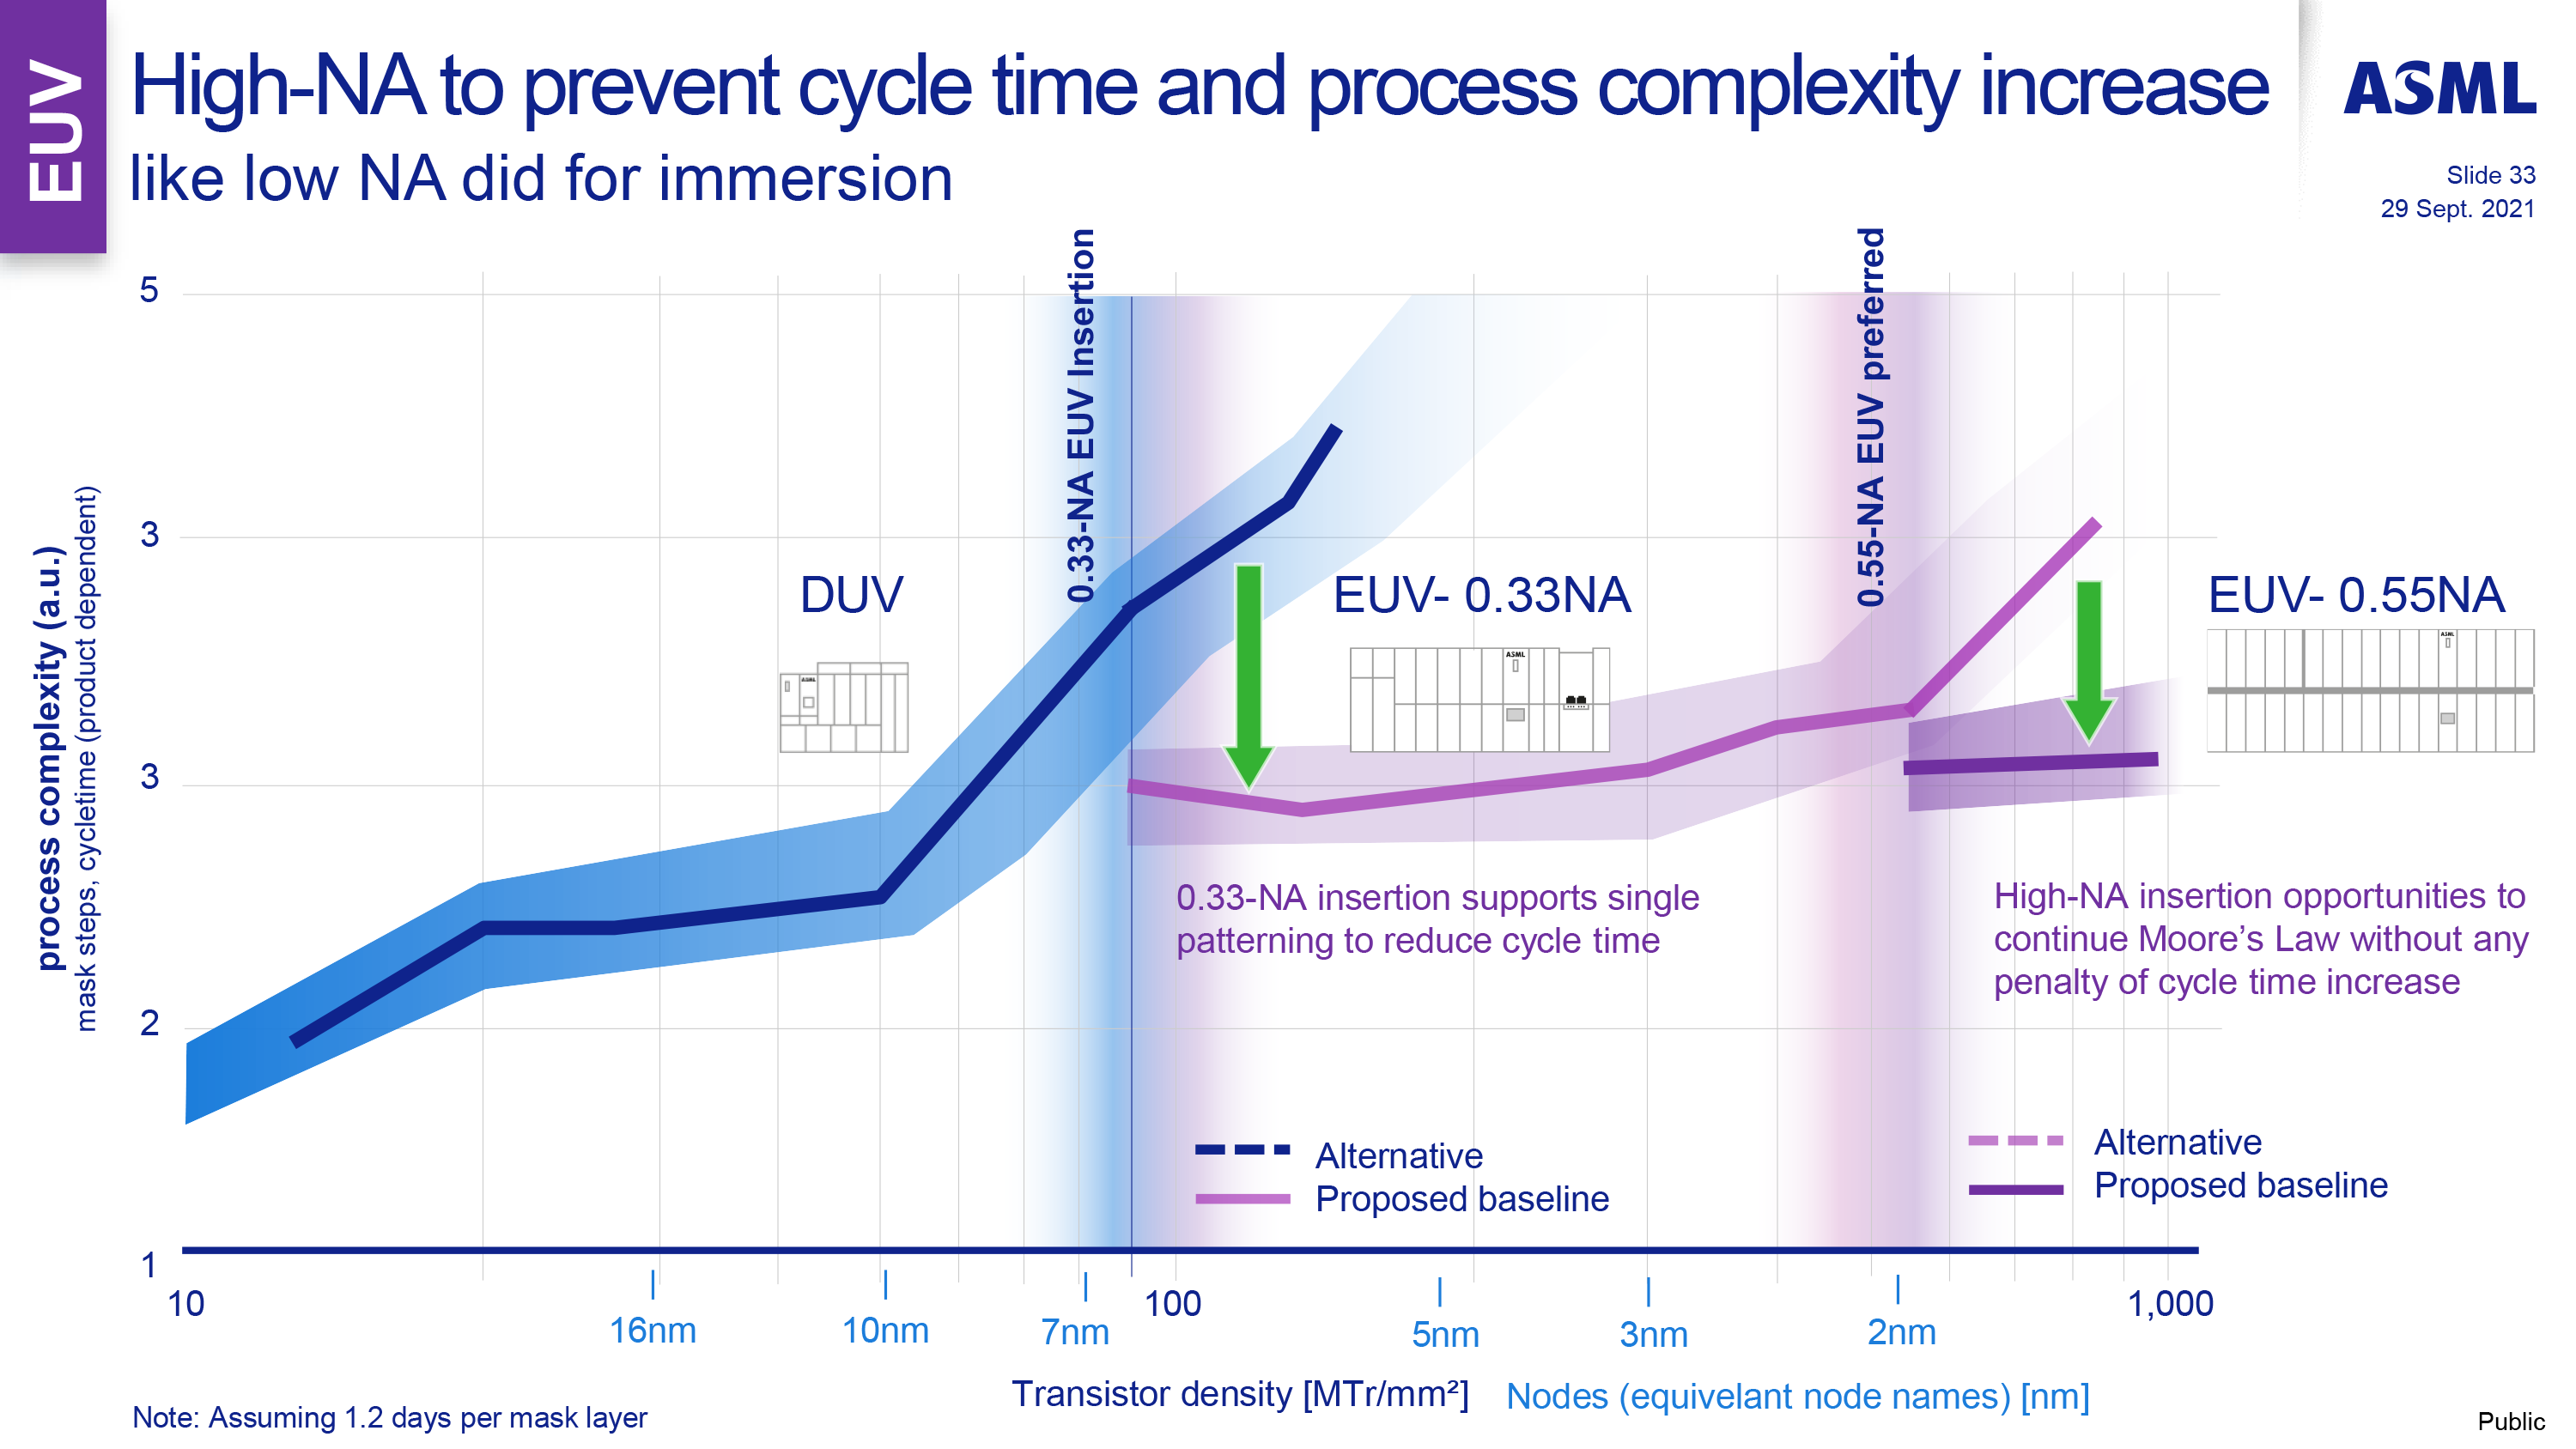
Intel Corporation (NASDAQ: INTC) and ASML Holding N.V. (NASDAQ: ASML) reached a significant manufacturing milestone, with more than one million wafers processed through High-NA extreme ultraviolet (EUV) lithography systems, according to a September 9, 2026, report from Yahoo Finance. This achievement, announced alongside Intel’s 10% stock price increase, underscores the growing importance of advanced chipmaking technology in meeting enterprise computing demands. The development also highlights the contrasting strategies of Intel and ASML versus Arm Holdings (NASDAQ: ARM) in the AI-driven semiconductor sector.
Intel and ASML’s High-NA EUV Milestone
The milestone marks a critical step in semiconductor manufacturing, with Intel and ASML demonstrating the scalability of High-NA EUV systems. These tools use a 0.55 numerical aperture lens to etch finer circuit patterns in a single exposure, reducing reliance on costly multi-patterning techniques. According to the Yahoo Finance article, Intel installed the first commercial High-NA system in 2024, and the recent processing of over one million wafers across certification, testing, and production signals operational maturity. This progress aligns with Intel’s broader efforts to leverage manufacturing advancements into pricing power, as noted in the report: The combination of commercial pricing power and verified High-NA wafer volume shows that the turnaround is shifting toward execution.
Intel’s stock surged nearly 10% following the announcement, with intraday trading volume exceeding $11 billion. This operational progress marks a clearer step from structural development into active yield realization,
the report stated.
Arm’s Licensing Model vs. ASML’s EUV Dominance
While Intel and ASML focus on manufacturing, Arm Holdings competes by licensing its energy-efficient CPU architecture to chipmakers. As of March 2026, Arm’s technology powers over 99% of smartphones and 350 billion chips globally, according to a September 2026 Yahoo Finance analysis. The company’s fiscal 2026 revenue reached $4.9 billion, a 22.8% year-over-year increase, with a net margin of 18.4%. Arm’s licensing model generates recurring royalty income, though it faces risks from open-source alternatives like RISC-V and reliance on the slowing smartphone market.
In contrast, ASML’s dominance in EUV lithography gives it a unique position in the semiconductor ecosystem. As of December 2025, ASML reported €32.7 billion in revenue, with a rise from the prior year, with a net margin of 29.4%. Its machines are essential for producing advanced chips, including those used in AI applications. The Yahoo Finance article highlighted ASML’s “legal monopoly” in EUV technology, as competitors have yet to replicate its capabilities. However, the company faces geopolitical risks, particularly export restrictions on high-tech equipment to China, and cyclical demand fluctuations. Despite these challenges, ASML’s free cash flow reached €11.1 billion in 2025, reflecting its financial strength.
Investor Considerations: Growth vs. Stability
Investors evaluating Arm and ASML must balance growth potential against stability. Arm’s faster revenue growth—22.8% in fiscal 2025—positions it as a play on AI-driven data center demand, though its lack of dividends contrasts with ASML’s shareholder returns. ASML’s higher net margin (29.4% vs. Arm’s 18.4%) and robust free cash flow suggest stronger operational efficiency, but its exposure to global semiconductor cycles introduces volatility. The Yahoo Finance analysis noted, ASML is ideal for income-oriented investors because it pays a dividend, while Arm does not. Shares in the maker of EUV lithography machines also sport a lower valuation.
Both companies face distinct risks. Arm’s reliance on smartphone demand and competition from RISC-V could limit its long-term growth, while ASML’s exposure to geopolitical tensions and capital-intensive R&D may affect profitability. However, their complementary roles in the chip supply chain—Arm’s architecture enabling design, ASML’s tools enabling fabrication—suggest that both will remain critical to AI advancements.
The Road Ahead for AI-Driven Semiconductor Demand
The interplay between Intel, ASML, Arm, and other players will shape the future of AI hardware. Meanwhile, Arm’s licensing model offers flexibility for chipmakers navigating diverse AI workloads. As data centers scale to meet AI demands, the ability to balance innovation, cost, and reliability will determine which companies capture the most value.
For investors, the choice between Arm and ASML reflects broader trade-offs in the AI economy. As the industry evolves, the success of these companies will hinge on their ability to adapt to shifting technologies and global dynamics, ensuring their relevance in an increasingly AI-centric world.