Economists expected a 3.6% increase, but Eurozone consumer price inflation accelerated to 3.8% year-over-year in September, driven largely by an energy price shock stemming from Middle East conflict. The hot reading intensifies pressure on the European Central Bank following its September 18 rate hike.
Consumer prices across the currency bloc rose faster than anticipated in September, driven by energy costs linked to the Iran war. Preliminary data from Eurostat showed the Harmonized Index of Consumer Prices climbed to 3.8% year-over-year, surpassing the 3.6% consensus expectation and accelerating from August’s final reading of 3.2%, as reported by FXStreet.
On a monthly basis, inflationary pressures grew at a pace of 0.6%, up from 0.4% in the prior release.
Energy Costs Drive September Acceleration Across Eurozone States
Energy inflation surged from 14.3% to 18.8% year-over-year, with monthly energy prices jumping 3.9%, according to data summarized by Actionforex. Diesel and petroleum prices hit record highs in Germany, France, Italy, and several other eurozone countries as military conflict in the Middle East slowed shipments of crude oil and refined fuels from the Gulf.
Based on Reuters coverage detailed by IndexBox, the harmonized inflation figure for France reached 3.4% year-on-year in September compared to 2.6% in August, whereas the Italian rate climbed sharply to 4.1% from 3.2% in the preceding month. In Spain, inflation climbed to 5.0% in September from 4.6% in August.
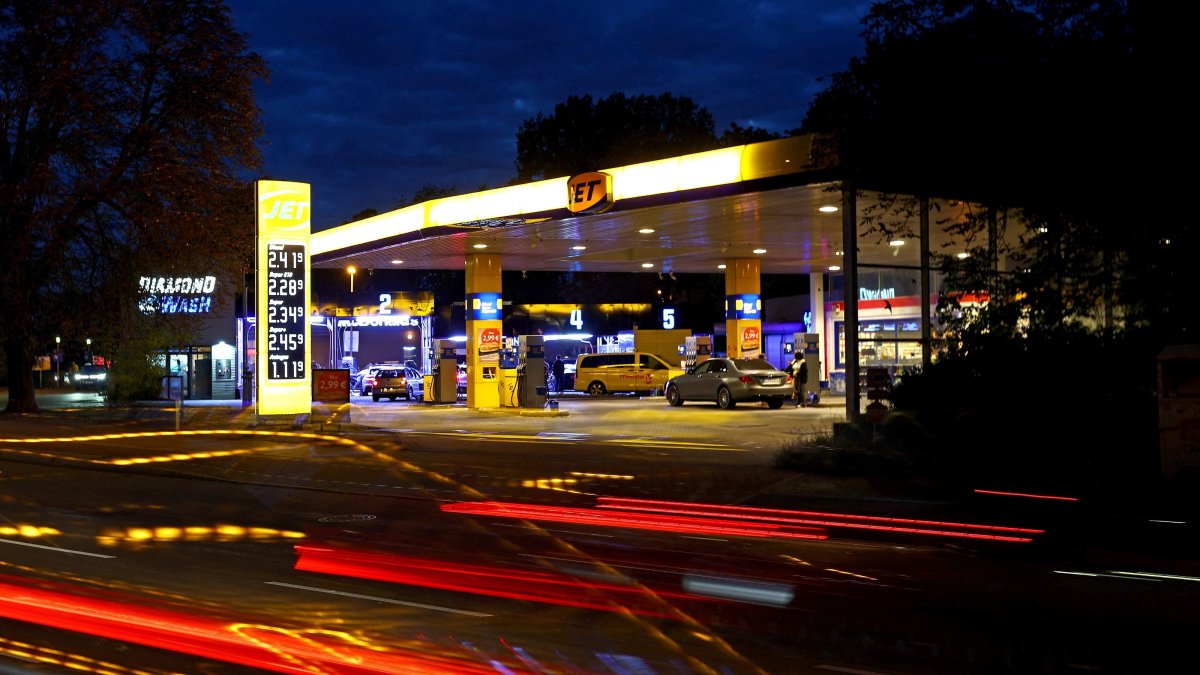
In Germany, Europe’s largest economy, the annual rate hit 3.3% — its fastest pace since December 2023 — based on preliminary data from Destatis. State-level readings confirmed the upward trend, with inflation rising in Bavaria, North Rhine-Westphalia, Lower Saxony, Baden-Wuerttemberg, and Hesse, noted by Maria Martinez for Reuters.
Early data released by the Italian National Institute of Statistics showed that Italy’s national consumer price index advanced 4.2% on an annual basis during September, marking a 0.9 percentage point increase from August’s 3.3% rate. Regulated energy price inflation grew from 18.6% to 25.9%, unregulated energy price inflation rose from 17.0% to 22.2%, and overall energy prices registered a 22.3% increase.
Core Inflation Measures Remain Muted Despite Hotter Headline Figures
Beneath the volatile headline numbers, underlying price pressures proved considerably more contained. Core HICP — which strips out energy, food, alcohol, and tobacco — rose by 2.5% year-over-year, exactly matching economists’ expectations and moving up modestly from August’s 2.4% reading.
Non-energy industrial goods inflation actually eased from 1.2% to 1.1%, demonstrating that the acceleration was not broad-based across all core retail categories. Food, alcohol, and tobacco inflation edged up from 1.1% to 1.4%, while services inflation increased from 3.0% to 3.2%, indicating some renewed domestic pricing firmness.
Mariana Monteiro of J.P. Morgan observed that while energy and food inflation both surprised on the upside, food inflation exceeded forecasts much more modestly.
European Central Bank Faces Intensified Policy Dilemma
Markets are now pricing in four additional interest rate hikes over the next year, building on the two increases implemented over the summer. Under its adverse scenario modeling, the ECB projects inflation to average 4.0% in both the fourth quarter of this year and the first quarter of 2027, with economists noting that current energy prices align more closely with that severe scenario than with the bank’s baseline projections.
Ahead of the flash release, ECB chief Christine Lagarde noted on Monday that a moderate policy response remains appropriate because the surge had not yet generated dangerous second-round effects across the bloc. Dirk Schumacher, chief economist at the German public lender KfW, remarked that the readings could ease immediate pressure for further monetary tightening, while Oxford Economics analyst Rory Fennessy suggested the data might alter the debate among policymakers.
August figures showed a 0.5% contraction in French consumer spending, alongside a public debt burden of 119% of GDP in the second quarter — an amount almost twice the 60% eurozone ceiling. ING analysts cautioned at a time when consumption is weakening and rising interest rates are exacerbating France’s fiscal difficulties that persistent inflation will constrain household purchasing power, predicting that price increases will likely stay above 3% throughout the remainder of 2026 prior to a gradual easing in 2027.