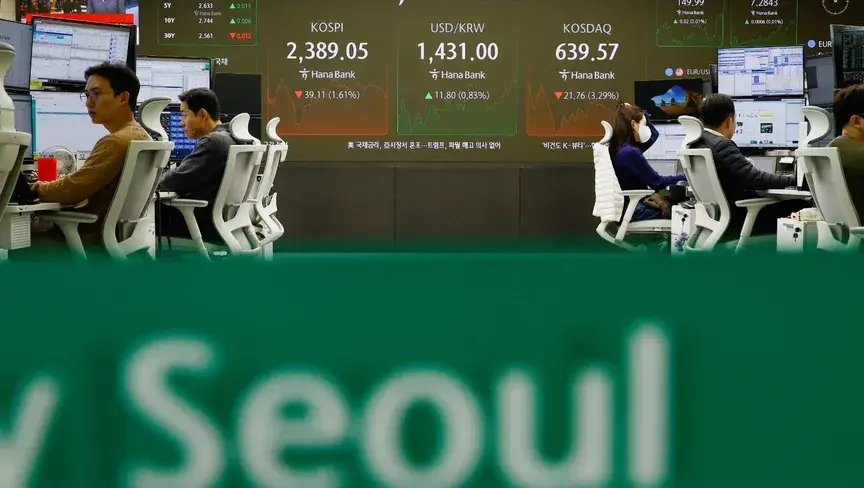
Global equities retreated on Thursday, October 22, 2026, as disappointing corporate earnings from major technology firms renewed doubts over artificial intelligence spending. The downturn coincided with rising Middle East tensions that pushed crude oil past $110 a barrel and fueled safe-haven demand for U.S. Treasuries.
Updated October 27, 2026
Equity markets faced severe selling pressure during Thursday sessions following mixed quarterly updates from industry giants. Futures on the Nasdaq 100 dropped 1.3%, while S&P 500 contracts declined 0.7%, according to financial market reporting. The retreat dismantled recent optimism about the durability of tech-led rallies and triggered sharp declines across international trading floors.
Technology Earnings Test Investor Confidence in Artificial Intelligence
Wall Street earnings reports failed to reassure investors who are increasingly questioning the massive capital expenditures required to build out artificial intelligence infrastructure. Markets are transitioning from an era driven purely by enthusiasm to one demanding concrete financial returns.

Markets are essentially telling us that we are moving away from trading based on AI hype and associated narratives, to a phase that now requires extremely high standards for what beats earnings expectations.
Kanhangh Singh, head of equity derivatives sales for Asia-Pacific at Barclays, via Bloomberg Television
Individual corporate reports highlighted the widening divide. Tesla shares fell 3.3% in extended trading after the electric vehicle maker reduced its capital expenditure forecast. Conversely, Meta Platforms saw its stock rise 2.2% after hours following plans to deepen its AI bets and fund large infrastructure commitments. Meanwhile, semiconductor equipment maker Lam Research slumped 7.4% after issuing earnings guidance that missed market estimates.
Market strategists have stepped up warnings regarding the sector’s valuation. Broadcom Chief Executive Officer Tan noted earlier in the week that the AI rally has attracted speculative investors resembling gamblers whose strategies lack a full understanding of the risks.
Asian Markets and Semiconductor Suppliers Bear the Brunt of Selling
The sell-off rippled heavily across Asia. The MSCI Asia Pacific Index dropped 1.5%, while South Korea’s Kospi index tumbled 3.3%. In Seoul, memory chip giants Samsung Electronics and SK Hynix suffered steep losses as investors weighed intensifying regional competition.
China’s CSI 300 Index retreated 1.3%, bringing it to the brink of a technical bear market. E-commerce shares in Hong Kong faced additional pressure after government officials urged stricter product quality controls. Tokyo’s Nikkei 225 fell 2.29%, reversing earlier gains as chip equipment suppliers retreated alongside American peers.
Geopolitical Pressures Drive Crude Oil Above $110 and Lift Safe-Haven Bonds
Compounding tech sector jitters, geopolitical developments in the Middle East drove energy markets sharply higher. Brent crude climbed roughly 2% to trade above $111 a barrel, fueled by supply disruption fears following a deadly attack on a Saudi oil field and subsequent U.S. State Department orders for select diplomats to depart the kingdom.
Global investors sought refuge in fixed-income assets. U.S. Treasury prices rallied across the yield curve, pushing the 30-year bond yield down by three basis points to 5.38%—its lowest level since September 23.
| Market Indicator | Direction | Movement / Level |
|---|---|---|
| Nasdaq 100 Futures | Down | -1.3% |
| S&P 500 Futures | Down | -0.7% |
| Brent Crude | Up | Above $111/barrel |
| U.S. 30-Year Treasury Yield | Down | 5.38% (lowest since Sept. 23) |
| Gold | Down | Below $4,100/oz |
| Bitcoin | Down | Near $82,800 |
Precious metals and cryptocurrencies faced downward momentum alongside equities. Gold retreated 1.2% to trade below $4,100 an ounce. Bitcoin also declined over 2% to trade near $82,800, reflecting diminished risk appetite as traders await upcoming earnings reports from major tech heavyweights Microsoft and Alphabet.
Update (October 23, 2026)
According to CNBC, market volatility intensified on Friday as the Cboe Market Volatility Index climbed 6% to 20.24, putting the VIX on track to close above 20 for the first time since early June following a 14% jump on Thursday.
Pre-market and early trading brought sharp moves across several sectors. Moderna shares fell 5.7% after a 25% drop on Thursday following a leaked partial data report on its Merck-developed cancer vaccine. Deckers tumbled 6.7% after its fiscal second-quarter revenue missed analyst expectations, and Gucci-parent Kering plunged 12% after reporting a 1% decline in same-store sales driven by a 6% drop for Gucci. Meanwhile, telecommunications stocks slid nearly 5% following reports that SpaceX is in talks to access at least 80,000 U.S. cell sites to become a wireless carrier, even as SpaceX shares received a boost from a PhillipCapital upgrade raising its price target to $250.
Update (October 26, 2026)
According to CNBC, stock futures rose on Sunday evening with S&P 500 futures up 0.4% and Nasdaq-100 futures gaining 0.6%, as traders anticipated central bank decisions this week from the U.S. Federal Reserve, the European Central Bank, and the Bank of Japan. Oil prices declined on Monday in Asia, with Brent futures falling to $15.19 a barrel following a late-week surge driven by reports of potential strikes on Iran. Meanwhile, France received a temporary reprieve as Moody's maintained its Aa3 credit rating and negative outlook.
Update (October 27, 2026)
According to CNBC, stock futures were little changed early Tuesday following a Wall Street winning session as traders awaited corporate earnings and the start of the Federal Reserve's two-day policy meeting. S&P 500 futures edged marginally higher, Dow Jones Industrial Average futures gained 123 points or about 0.2%, and Nasdaq-100 futures added 0.1%.
The artificial intelligence trade received a boost after Anthropic filed to go public at the Nasdaq, following SpaceX's June listing. Tuesday's earnings docket includes Coca-Cola, Robinhood, and Boeing, with Microsoft, Alphabet, and Amazon reporting later in the week. The Fed is widely expected to keep interest rates unchanged.