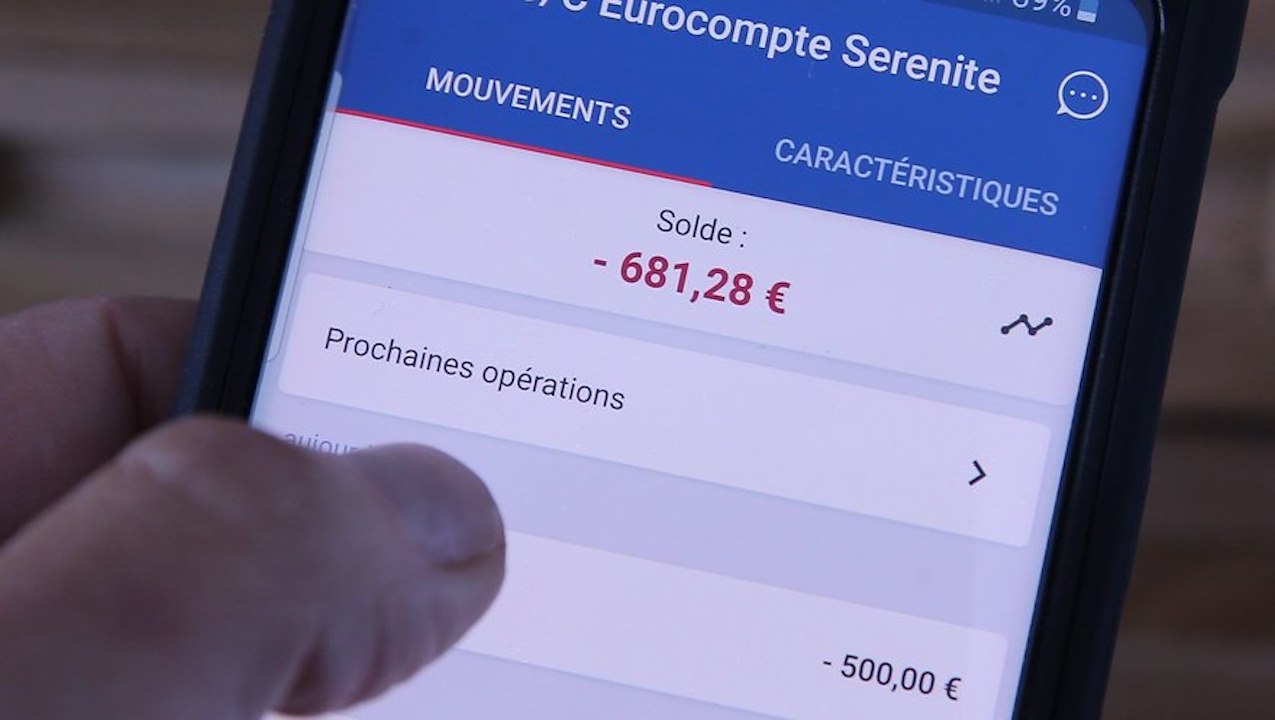
Nearly one in five people in France now slip into a negative bank balance every month, driven by soaring living costs. As households struggle with rising energy and food prices, stricter European credit rules set to take effect on November 20 will tighten the review process for even small overdrafts under 200 euros.
Financial pressure on households across France continues to mount, with the latest figures highlighting a steady climb in routine bank overdrafts. A survey released by Panorabanques shows that 18 percent of respondents see their accounts drop into the red on a monthly basis according to the comparative study. That proportion marks an increase from 16 percent the previous year, underscoring how persistent inflation strains basic household budgets. Anna Meylacq, spokesperson for Panorabanques, noted that 43 percent of people in the country experience a negative balance at least once per year while 18 percent face it every month, reflecting structural pressure on household margins as reported by Economie Matin and Social Mag.
On an annual scale, the footprint of financial strain is even wider. Nearly half of all households—43 percent—experience a negative account balance at least once a year as reported by the platform’s findings, up from 41 percent. For most people, these shortfalls are modest and temporary. Roughly 65 percent of all overdrafts remain under 200 euros and resolve themselves in less than a week, functioning as a short-term buffer against daily expenses such as grocery and utility bills.
Rising Inflation and Everyday Costs Drive Household Shortfalls
When asked what pushes their accounts into negative territory, participants pointed directly to the escalating cost of essentials. Price increases for energy, food, and fuel lead the list of factors compiled in the research, followed by unexpected large expenses and general financial situations described as difficult. These pressures coincided with widespread demonstrations against the high cost of living that brought crowds into the streets on October 17, 2026, as noted by AbcBourse.
The financial impact extends beyond the initial deficit. Banks apply various charges to accounts in the red, including debit interest known as agios, intervention fees for transactions requiring manual handling, and charges for payment rejections as detailed by the comparative data. Panorabanques also recorded that minimum quarterly charges across 46 surveyed banks ranged from 1.50 to 10 euros, averaging 6 euros according to data published earlier in the year. Critics argue these cumulative costs weigh disproportionately on modest budgets.
New European Rules Set Solvency Checks for Small Overdrafts
Against this backdrop of financial strain, regulatory oversight is shifting. On November 20, France will transpose a European Union consumer credit directive into national law via ordinance mechanisms, specifically through ordinance No. 2025-880 of September 3, 2025, which implements EU directive 2023/2225 as detailed by legal and economic commentators. The change alters the treatment of small authorized overdrafts under 200 euros—often termed cash facilities—which previously enjoyed a flexible approval process without rigorous individual solvency checks.
Under the updated framework, institutions must examine a client’s financial situation before granting any new credit facility, evaluating income, expenses, assets, and liabilities. Existing authorizations granted prior to the implementation date remain valid, but future requests will face stricter scrutiny to align with consumer protection standards.
Political Debate and Concerns Over Financial Exclusion
The regulatory shift has sparked sharp political debate. Some critics previously labeled the stricter evaluation requirements as excessive surveillance on low-income citizens during legislative discussions, with figures like Clémence Guetté denouncing the approach on RMC as a form of policing the poor as reported in broadcast interviews. At the same time, banking sector representatives emphasize that mandatory proportionality rules aim to preserve broad access for temporary cash flow adjustments rather than impose a blanket ban.
Welfare advocates warn that mandatory solvency reviews could inadvertently push vulnerable consumers toward more expensive alternatives, such as revolving credit or high-cost borrowing, if traditional overdraft access is denied due to strict risk models. Whether banks will broadly restrict access or simply formalize existing assessments is the central question for households managing their finances ahead of the November deadline.