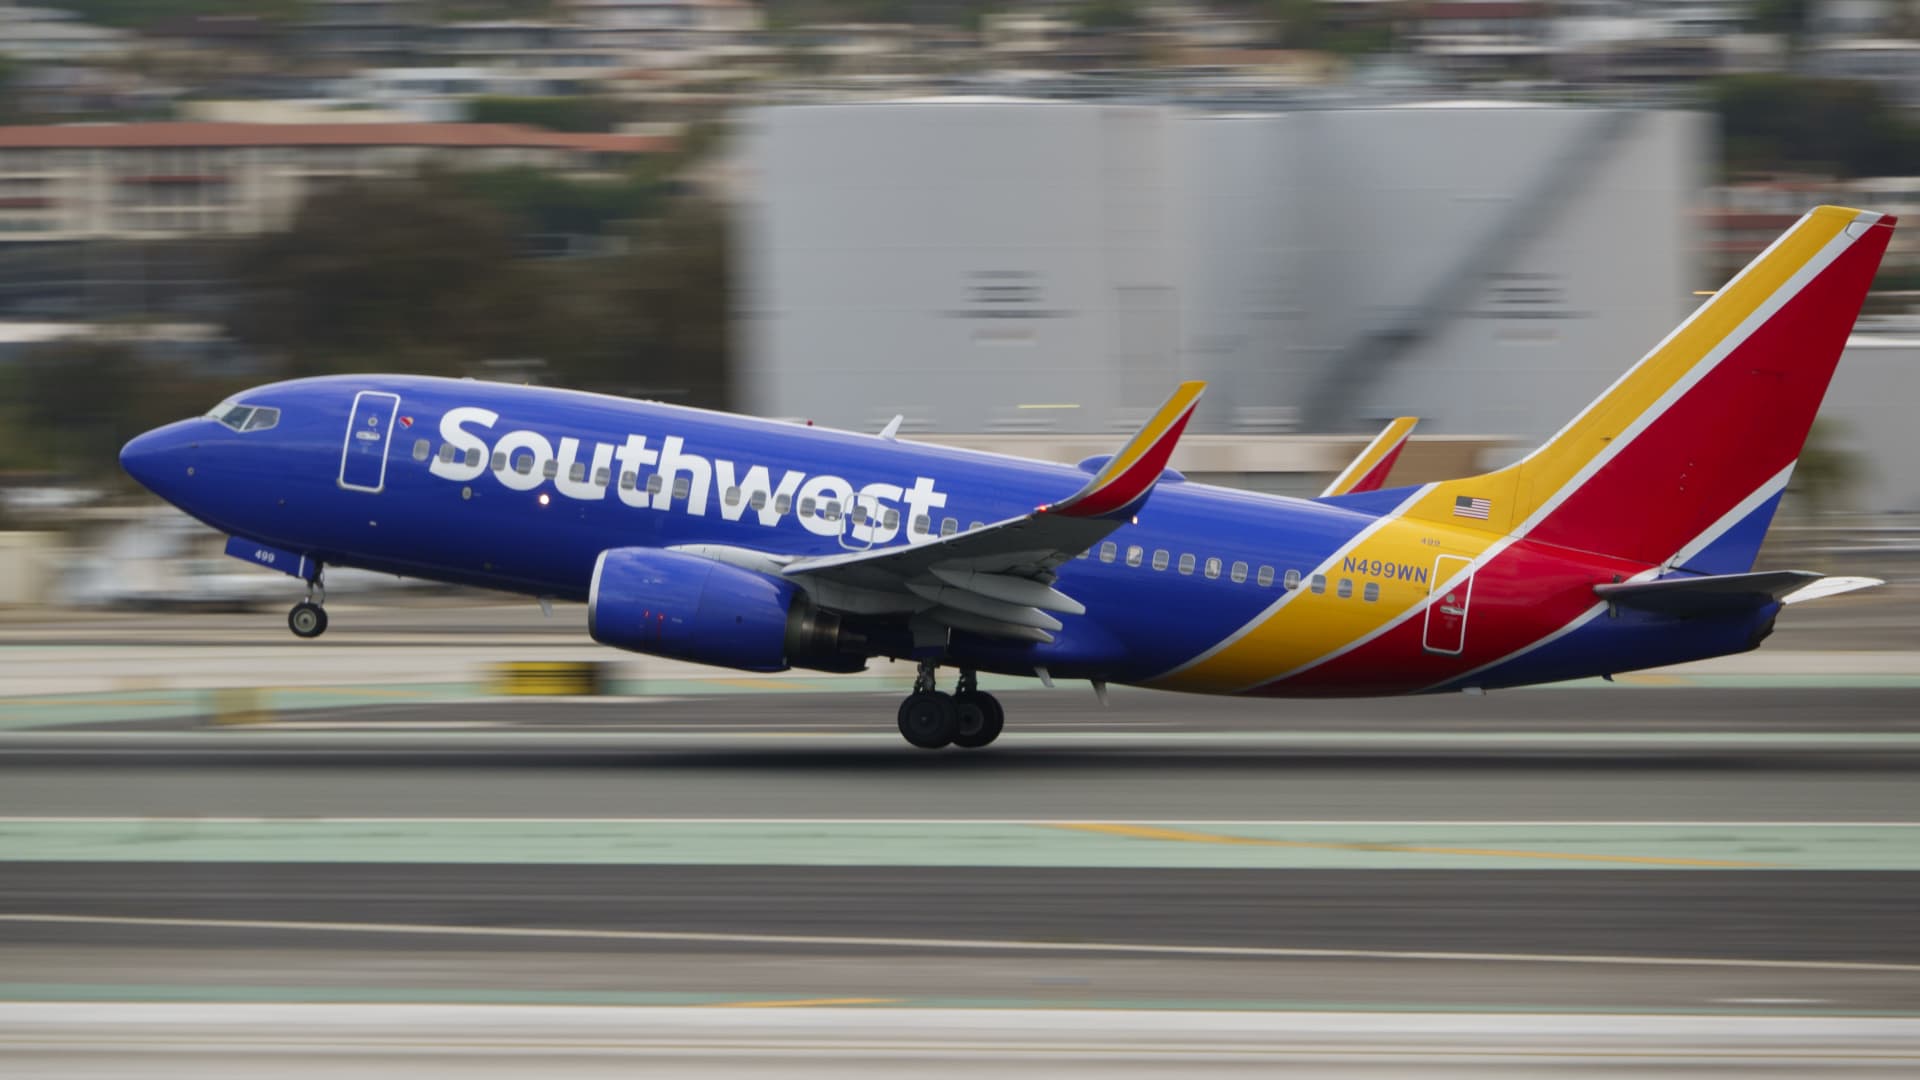
Southwest Airlines cut its 2026 profit forecast to between $2.60 and $2.85 per share, joining major carriers lowering expectations as jet fuel costs mount.
Southwest Airlines became the third major U.S. carrier to scale back its full-year outlook, marking the third time this year that the carrier has reduced its profit projections. The downward adjustment brings its adjusted earnings per share target to a range of $2.60 to $2.85, a significant retreat from a previous July forecast that reached as high as $4.25 per share as reported by Cnbc.
The financial reset reflects mounting pressure across the commercial aviation sector. Jet fuel expenses have climbed well past initial estimates, forcing airlines to absorb or pass along steeper operating costs even as travel demand shows resilience.
Third-Quarter Revenue Growth Outpaces Profit Warnings
Financial results for the third quarter present a dual narrative of rising revenue set against tightening margins. Operating revenue rose more than 21% to $8.42 billion, comfortably exceeding Wall Street consensus estimates of $8.25 billion tracked by LSEG according to earnings figures.

Net income climbed to $270 million, or 55 cents a share, marking a sharp recovery from $54 million, or 10 cents a share, during the same period a year earlier. On an adjusted basis, the airline reported 66 cents per share, topping analyst expectations of 58 cents based on consensus estimates.
Airfares continued an upward trajectory as the carrier pushed through higher ticket prices. The average passenger fare reached $231.69 during the third quarter, representing a 27% increase over the same three-month window in 2025. That figure excludes add-on charges such as baggage fees as detailed by the airline.
Fuel Bill Escalation Across the Airline Sector
The root cause behind the lowered earnings guidance lies in soaring energy expenses. Southwest reported paying $3.92 per gallon for jet fuel in the third quarter, surpassing its internal projections of $3.70 to $3.75, and anticipates paying as much as $4.55 per gallon during the final quarter of the year according to Skift.
This cost burden is not isolated to a single carrier. Delta Air Lines and United Airlines also lowered their profitability forecasts for the remainder of the year. Industry fuel estimates show United guiding toward a fourth-quarter fuel expense of $4.80 per gallon, while Alaska Airlines expects to pay between $4.65 and $4.85 per gallon as reported across sector coverage.
Despite climbing fares and strong top-line revenue, customer volume dipped slightly. The number of revenue passengers carried dropped 3.2% to 33.47 million travelers compared to the previous year as noted in operational disclosures.
Overhauling Business Models Amid Upmarket Shifts
The financial turbulence arrives as Southwest systematically dismantles its legacy operating model. Under pressure to maximize revenue, the carrier has phased out traditional mainstays like open seating and two complimentary checked bags, replacing them with assigned seating options and baggage fees according to company announcements.
Parallel to these structural changes, the airline is pursuing an upmarket transformation. Plans include opening airport lounges in four U.S. cities next year, revamping its loyalty rewards program, and evaluating the addition of long-haul international routes as outlined by executive leadership.
For the upcoming fourth quarter, Southwest projects adjusted per-share earnings between 55 cents and 80 cents, with unit revenue expected to grow as much as 21% year over year while capacity expands up to 4% based on quarterly guidance. Executives have scheduled a capital markets day in New York for March 2027 to detail the longer-term strategy according to company disclosures.