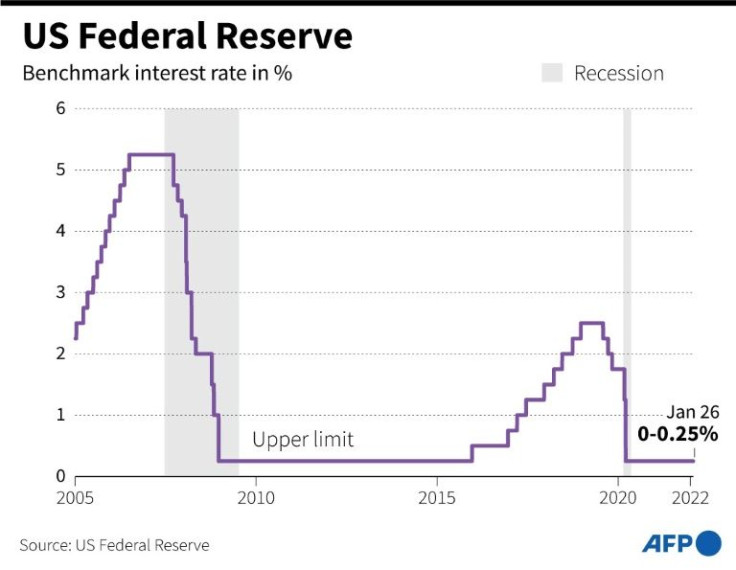
The US Federal Reserve raised its benchmark interest rate by a quarter percentage point to 3.75–4% on September 16, 2026, marking its first hike since 2023 and signaling a shift toward tighter monetary policy amid persistent inflation and global economic pressures.
The Federal Reserve’s decision to raise its benchmark interest rate by a quarter percentage point to 3.75–4% on September 16, 2026, marked its first policy tightening since 2023 and underscored a global alignment among central banks to combat inflation. The move came as the US economy showed resilience, with strong labor markets, productivity growth, and capital investment, while geopolitical tensions and energy price shocks continued to fuel price pressures. The Fed’s action followed similar steps by the European Central Bank and the Bank of Japan, reflecting a synchronized approach to balancing inflation control with economic stability.
A Global Policy Shift Amid Persistent Inflation
The Fed’s rate hike, the first since 2023, was driven by concerns over inflation remaining elevated despite earlier policy easing. Chairman Kevin Warsh emphasized that progress toward the central bank’s 2% inflation target had been “modest,” with the Personal Consumption Expenditures Price Index (PCE) still at 3.7% annually as of July 2026. Progress over the past two years has been modest,
Warsh stated, adding that inflation trends had not meaningfully improved.
This sentiment echoed broader global challenges, as the Monetary Authority of Singapore (MAS) also tightened its policy in July 2026, raising the rate of appreciation of the Singapore dollar to counter inflationary pressures from energy prices and domestic investment growth.
The alignment between the Fed and smaller economies like Singapore highlights how inflationary forces—driven by geopolitical conflicts, supply chain disruptions, and AI-driven capital spending—are forcing central banks to adopt similar strategies. Salman Ahmed, global head of macro and strategic asset allocation at Fidelity International, noted that geopolitical fragmentation, energy security, and the capital intensity of the AI investment cycle all point towards a world in which inflation is likely to remain more persistent.
This view was echoed by Sheana Yue of Oxford Economics, who warned that tighter monetary policy globally could weigh on real demand and export volumes, though she also pointed to potential offsets, such as Singapore’s role as a refining and re-export hub benefiting from higher energy prices.
Warsh’s Hawkish Signals and Market Reactions
Chairman Kevin Warsh’s speech at the Jackson Hole economic symposium in August 2026 signaled a more hawkish stance than previous communications. While he avoided providing explicit forward guidance, his remarks suggested that further rate hikes could be on the horizon. We must be confident that underlying inflation is moving to our objective, clearly and at sufficient speed,
Warsh said, a statement that analysts at Capital Economics described as far clearer—and hawkish—than his last press conference appearance.
CME Group’s FedWatch tool indicated a 57.4% chance of another 25-basis-point hike at the Fed’s next meeting in mid-September 2026, reflecting market anticipation of continued tightening.
The Fed’s decision sent ripples through financial markets. US stocks initially fell after the rate hike, as higher borrowing costs weighed on valuations, but tech stocks—seen as more resilient to rate hikes—held up better. James Ooi, market strategist at Tiger Brokers in Singapore, noted that the stronger growth and higher profit margins of technology companies relative to traditional sectors could help offset the impact of higher rates.
However, the broader implications of sustained higher rates remain uncertain, with concerns about their effect on global trade flows and emerging market currencies.
Political Tensions and the Path Forward
Interest Rates in the United States should be 1 per cent, or less,
Trump asserted, framing the Fed’s actions as a barrier to economic growth. His comments highlighted the growing political tension between the administration and the central bank, particularly as the Fed’s new leadership under Warsh has taken a more inflation-focused approach. Trump’s push for rate cuts contrasted with the Fed’s emphasis on price stability, with Warsh stating that It’s the Fed’s job to make sure that inflation expectations do not get unanchored.

The Fed’s updated quarterly economic projections revealed that 16 of 18 policymakers anticipated at least one more rate hike by the end of 2026, with only two expecting rates to remain stable. This divergence within the central bank underscores the challenge of balancing inflation control with economic growth.
Looking ahead, the Fed’s next steps will depend on incoming data, particularly on inflation trends and the impact of higher rates on economic activity. With the US economy showing resilience and global central banks maintaining a tight policy stance, the path to returning to the 2% inflation target remains uncertain.
Meanwhile, the ongoing conflict in the Middle East and the trajectory of AI investment will continue to shape inflation dynamics, making the coming months a pivotal period for global monetary policy.