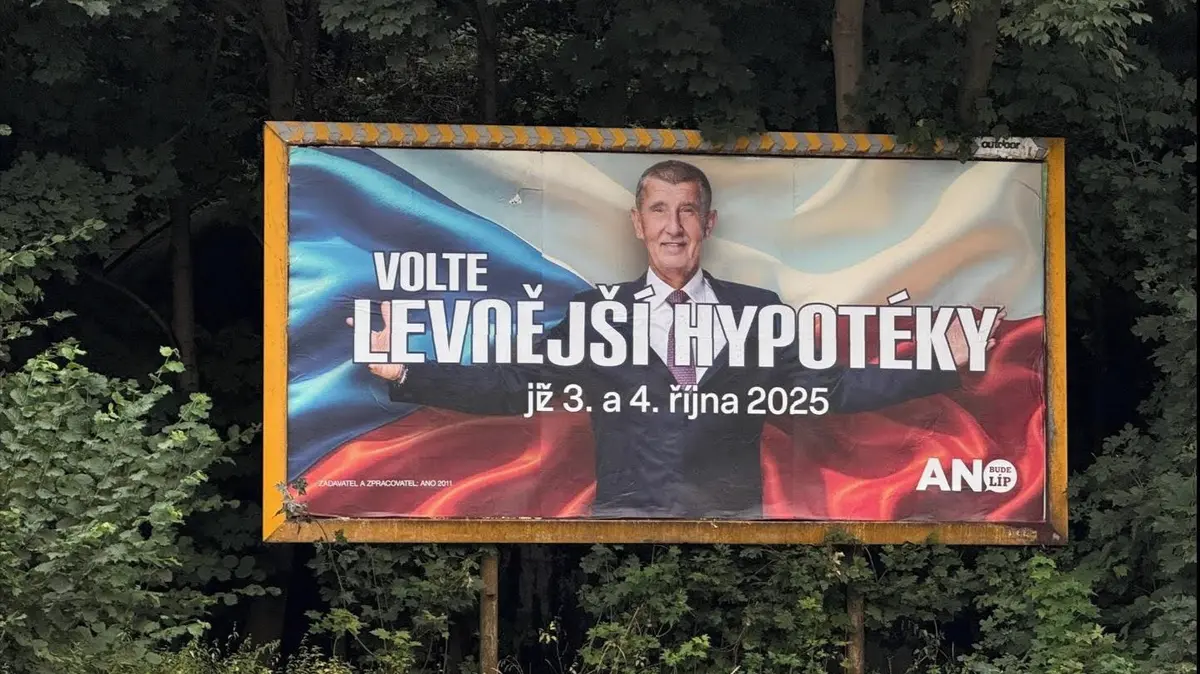
Average mortgage rates in Czechia have climbed to 5.79 percent despite pre-election pledges of cheaper housing loans.
Mortgage Rates Climb Despite Campaign Pledges
Average offered mortgage rates reached 5.79 percent, up from the 4.91 percent recorded last October, according to Swiss Life Hypoindex data. During the previous election campaign, movement ANO advertised promises that financing a home would become more affordable.
For an average household taking out a 3.5 milionu crown loan over a 25-year term, that increase translates to annual repayments higher by roughly 22 tisíc crowns. Finance Minister Alena Schillerová recently targeted commercial financial houses on social media, while Andrej Babiš previously blamed the central bank for keeping the base interest rate too high. European Parliament member Tomáš Zdechovský noted that such developments demonstrate how limited those pre-election promises truly were.
External Pressures Push Borrowing Costs Higher
Rates for three-year fixed products, which hovered around 3.4 percent prior to the conflict involving the United States and Iran, have now climbed to 4.9 percent. The price of credit primarily depends on the interest rates commercial institutions charge one another when borrowing funds.
Tom Kadeřábek, head of the product department at Swiss Life Select, pointed out that cheaper mortgages will not emerge from political pressure placed on the Czech National Bank, but only when inflation and financial markets allow it. Geopolitical tensions have driven up global oil and gas prices, fueling wider inflation concerns.
The state budget carries a planned deficit of 386 miliard crowns, creating a proinflationary risk that pushes market rates higher. Michal Bajer, executive director of Půjčka.co, stated that when the government operates with an enormous debt, it must issue an immense amount of state bonds and offer higher yields to attract investors, thereby draining available capital from the market and raising the price of money for everyone else.
Borrowers Face Hard Choices as Fixed Periods End
Lower financing costs will materialize only when inflation levels and financial markets permit a natural change. Industry specialists suggest that relief will not arrive through government decrees.
Mortgage brokers recommend that clients actively negotiate terms directly with their financial institutions, particularly individuals whose fixed-rate periods are coming to an end, as early engagement can yield better negotiating positions. Borrowers facing rate adjustments in the coming months are advised to take a proactive approach rather than waiting for systemic changes.