The Drewry Intra-Asia Container Index (IACI) rose 2% to $1,518 per 40ft container as typhoon disruptions and port congestion tightened supply, while Maersk overtook COSCO as the region’s largest intra-Asia carrier, according to recent reports.
The increase was driven by typhoon-related disruptions, port congestion, and carriers implementing blank sailings to manage capacity. Rates from Shanghai to Southeast Asia, including Ho Chi Minh City and Manila, surged 7% to $1,377 and $1,062 per 40ft container, while transhipment hubs like Singapore and Tanjung Pelepas saw 4% gains to $2,073 and $2,056, respectively. Meanwhile, rates from Busan and Yokohama to Shanghai rose 7% and 5% to $146 and $116, respectively.
Carriers Shift as Market Dynamics Change
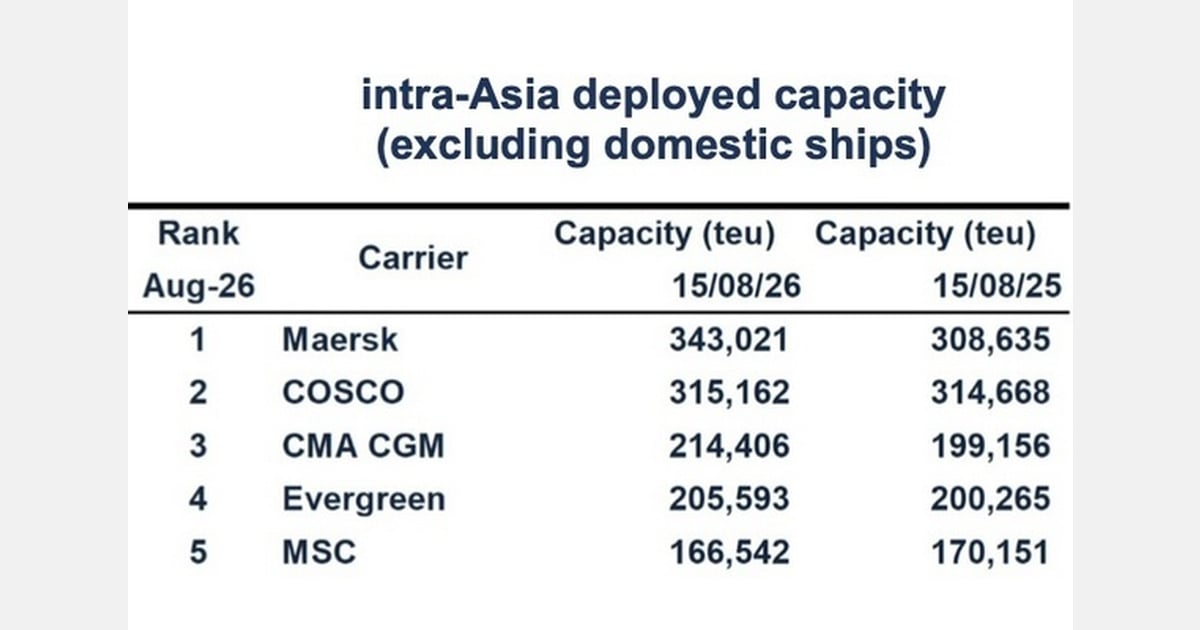
Maersk deployed over 340,000 TEU across intra-Asian services by mid-August, buoyed by its Gemini Cooperation network. Despite operating more than 120 ships, COSCO remained second, with stagnant capacity. CMA CGM added 15,000 TEU, overtaking Evergreen for third place, while SITC retained its crown as the largest regional operator with 109 ships and around 157,000 TEU. The Danish carrier had 108 ships deployed in the region, averaging 3,176 TEU, the largest average vessel size among leading intra-Asia operators. Mainline operators accounted for 63% of deployed capacity despite fewer ships than regional carriers, with their vessels averaging 2,699 TEU compared to 1,338 TEU for regional operators. Total capacity on international intra-Asia services, excluding domestic trades, reached just under 2.6 million TEU, up 6.2% year-on-year.
Alphaliner reported that Maersk’s fleet growth followed a around 34,000 TEU year-on-year increase, driven by the Gemini Cooperation’s hub-and-spoke model, which uses Asian shuttle services to feed main east-west loops. COSCO’s deployed capacity remained virtually unchanged from the previous year, despite operating more than 120 ships. CMA CGM’s 15,000 TEU expansion placed it third, surpassing Evergreen. SITC, the largest regional operator, maintained 109 ships and around 157,000 TEU, connecting smaller and niche ports. The intra-Asia market saw more than 80 carriers operating, with mainline operators controlling 63% of capacity. The IACI Composite Index hit a record high for the sixth week in a row due to typhoon-related issues and port congestion causing capacity constraints.
Rates and Costs Amid Future Outlook
Freight rates remained resilient amid geopolitical tensions and rising bunker costs, with Brent crude trading above $100 per barrel. CMA CGM imposed an emergency $75 per TEU fuel surcharge on all intra-regional trade lanes, effective 1 October. Drewry expects rates to stabilise in the coming weeks as Golden Week volume dips help clear backlogs, though the deteriorating Middle East situation kept Shanghai–Jebel Ali rates elevated at $8,662 per 40ft container. OOCL’s new China–Cambodia–Thailand Service (CCT4), launching 23 October 2026, aims to add capacity and direct links between South China and Southeast Asia. Rates to North Asia, including Busan, Kaohsiung, and Yokohama, remained broadly stable.
Shanghai and Ningbo experienced vessel congestion and scheduling delays, with average wait times amounting to 82 hours and 56 hours, respectively, during Week 39. Drewry anticipates rate stabilization in the near future as the decline in Golden Week traffic aids in reducing congestion and lowering costs on certain Southeast Asia routes. The IACI Composite Index has maintained record levels this month due to ongoing geopolitical and typhoon-related disruptions impacting supply chains and capacity availability. Spot rates from China to Southeast and South Asia increased this week, driven by high pre-Golden Week demand, reduced effective capacity, and continuous network adjustments after operational disruptions. The Drewry Intra-Asia Container Index (IACI) reports actual spot container freight rates for 18 route-specific indices, including Busan-Shanghai, Ho Chi Minh City-Shanghai, Jakarta-Shanghai, and others.
Context and Discrepancies in Market Data
Freshplaza also noted the intra-Asia market’s total capacity reached just under 2.6 million TEU, a 6.2% annual increase, with mainline operators controlling 63% of deployed capacity despite fewer ships than regional carriers. The IACI Composite Index hit a record high for the sixth week in a row due to typhoon-related issues and port congestion causing capacity constraints. Carriers implemented empty sailings and skipped ports to control capacity, with increased operational expenses contributing to rising rate pressures.
Spot rates from China to Southeast and South Asia increased this week, fueled by strong pre-Golden Week demand, reduced effective capacity, and continuous network modifications after operational issues. The IACI Composite Index has maintained record levels this month due to ongoing geopolitical and typhoon-related disruptions impacting supply chains and capacity availability. Drewry’s Intra-Asia Container Index (IACI) provides actual spot container freight rates for key intra-Asia trade routes, with the Index being updated weekly starting 02 Jan 26. The Index consists of 18 route-specific indices representing individual shipping routes and a composite index, all reported in USD per 40ft container. The Drewry Intra-Asia Container Index (IACI) increased 1% last week to US$1,323 per FEU, with the IACI Composite Index at record levels.
What remains unclear is whether the current rate levels will persist beyond the Golden Week period.
Ahmed Ibrahim World Editor