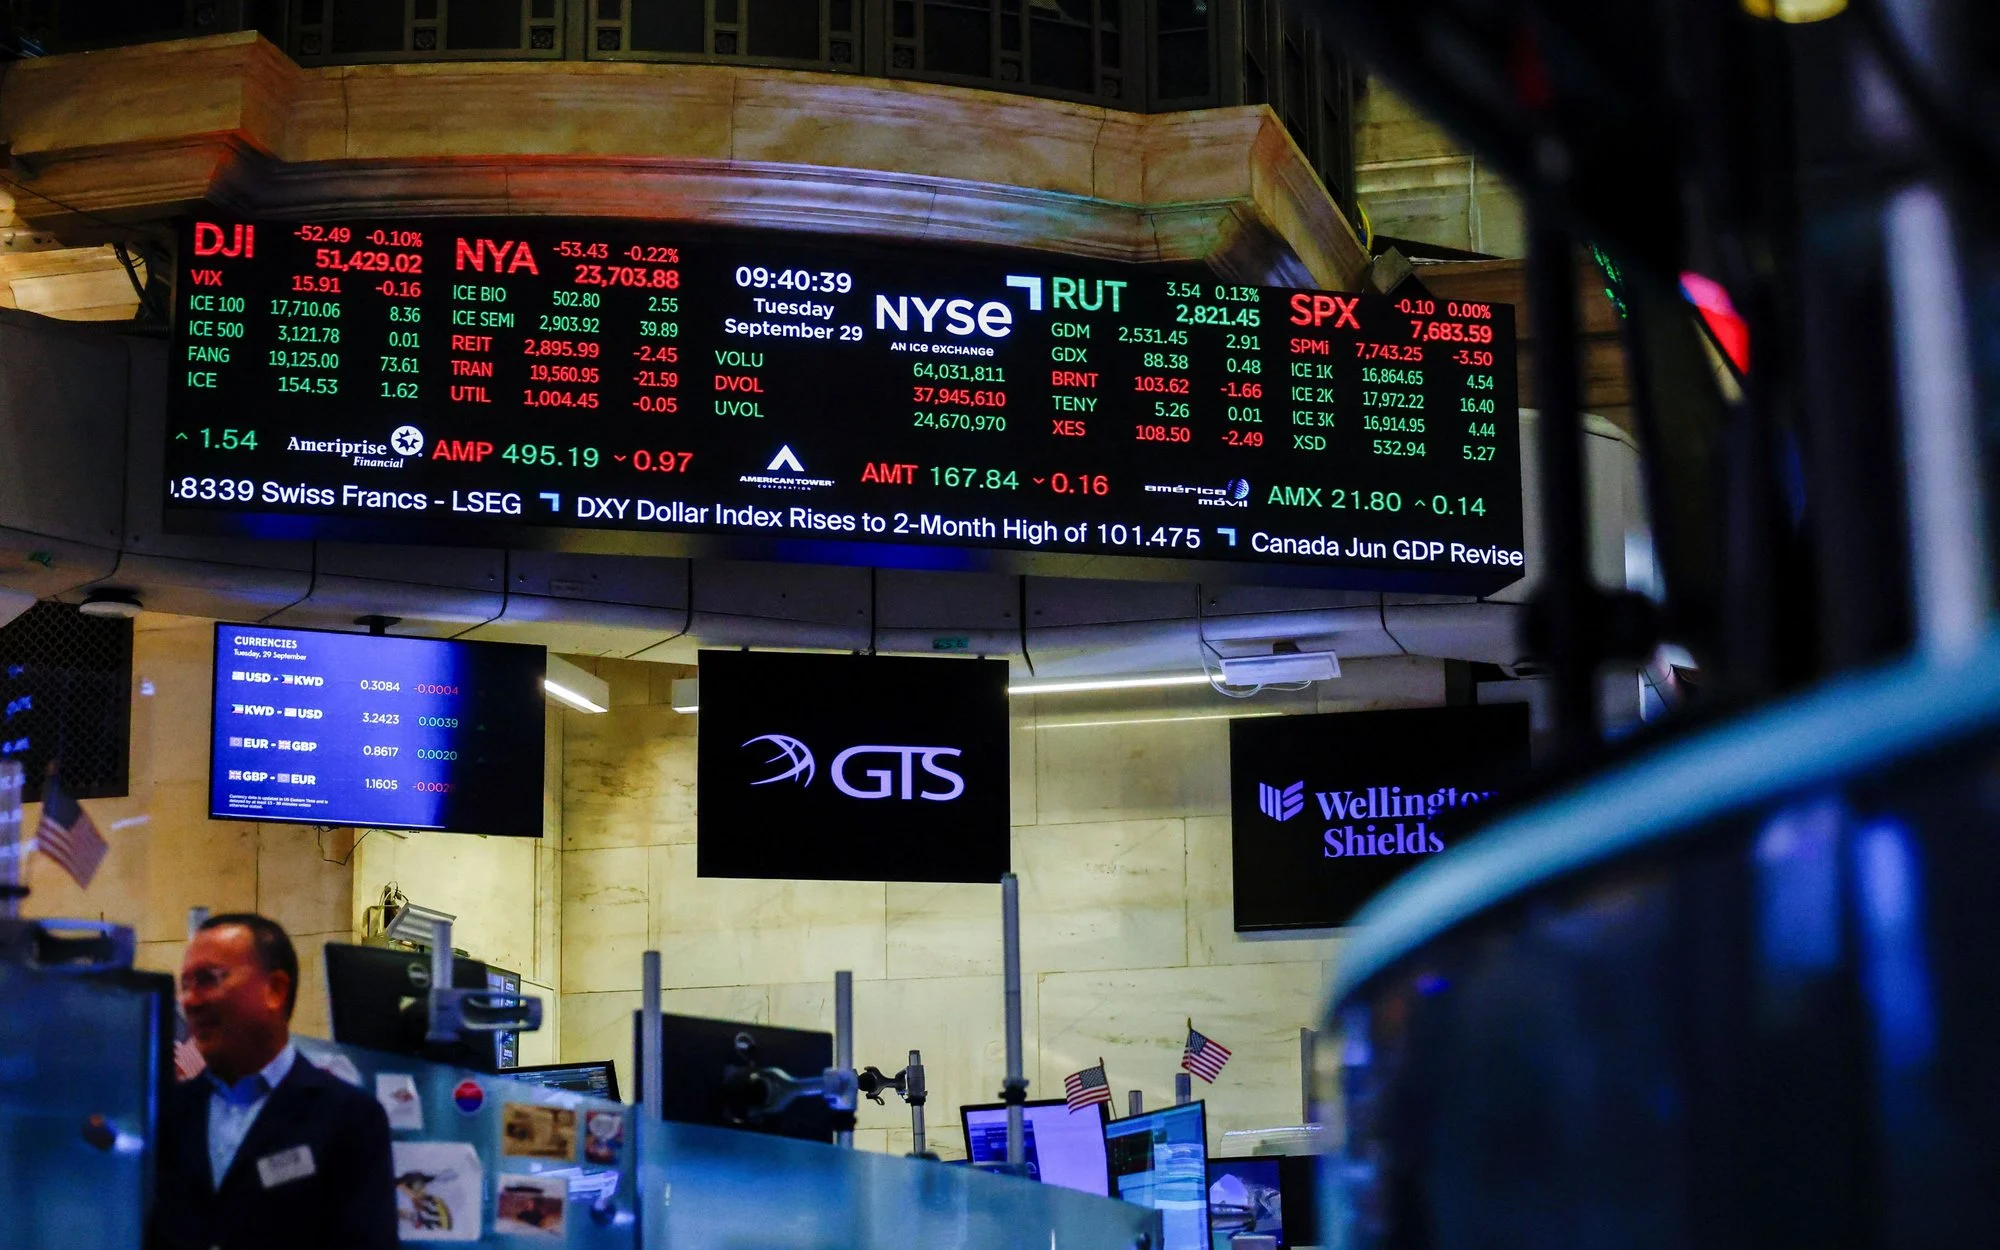
Global financial markets experienced a turbulent week marked by sharp swings in government bond yields, volatile energy prices, and rapidly shifting expectations regarding monetary policy, according to reports from Analizy.pl, Comparic.pl, Vietnam.vn, and Forexclub.pl. While sovereign debt markets faced a severe sell-off that drove yields to multi-year highs, Wall Street equities managed a late-week rebound as cooler-than-expected employment data drastically reduced the perceived likelihood of an imminent interest rate hike by the Federal Reserve.
Global Markets Navigate Surging Bond Yields and Shifting Federal Reserve Expectations
The bond market turmoil saw US Treasury yields climb significantly, driven by inflation concerns tied to high oil prices, heavy debt supply, and potential pressures from hedge funds scaling back “basis trade” strategies. US 10-year Treasury yields surpassed 5.35 percent on Thursday, marking their highest level since 2002, while 30-year yields briefly touched 5.6206 percent, a peak not seen since June 2002. European debt was similarly affected, with German 10-year yields rising above 3.6 percent and Polish 10-year yields briefly reaching 6.5 percent. Analysis from Forexclub.pl noted that while macroeconomic factors underpinned the sell-off, the partial reduction of leveraged basis-trade positions—evidenced by a drop in short futures values—added secondary supply pressure to the cash bond market.
Equities Prove Resilient Amid Technology Sector Support
Despite the sharp rise in borrowing costs, the downturn in broader stock markets remained relatively contained, supported by ongoing enthusiasm for artificial intelligence and major technology companies. On Wall Street, the week concluded with a late-session rally on October 2, after the US Department of Labor reported that nonfarm payrolls grew by only 29,000 in September—far below economists’ forecasts of 90,000—and unemployment ticked up to 4.2 percent.
Robert Bernstone, trading director at SummitTX Capital, noted that the soft employment data served as a positive signal indicating that the economy was not overheating. For the full week, the S&P 500 rose 0.73 percent to 7,722.72, the Nasdaq Composite gained 1.19 percent to 27,190.86, and the Dow Jones Industrial Average added 0.49 percent to 51,176.96, according to Vietnam.vn. CME FedWatch data indicated that the probability of a Federal Reserve rate hike in October plunged to roughly 22.7 percent following the jobs report, down sharply from roughly 64 to 68 percent earlier in the week.

Earlier Market Dynamics and Inflation Pressures
Earlier in the week, sentiment had swung sharply toward tighter monetary policy as inflation data surprised to the upside across multiple regions. In Poland, preliminary estimates showed consumer price inflation accelerating to 4.0 percent year-over-year in September, moving above the National Bank of Poland’s target band for the first time since June, largely driven by a 36.1 percent annual surge in fuel prices. Eurozone inflation similarly accelerated to 3.8 percent in September, complicating the European Central Bank’s policy path as rising energy costs amplified broader price pressures.
As markets look ahead, investors continue to weigh the delicate balance between softening economic activity, persistent inflation risks, geopolitical tensions affecting energy flows through regions such as the Strait of Hormuz, and high valuations for artificial intelligence-driven equities. Questions remain over whether future macroeconomic releases will confirm a sustained cooling of price pressures or if the recent respite in bond yields will prove temporary.