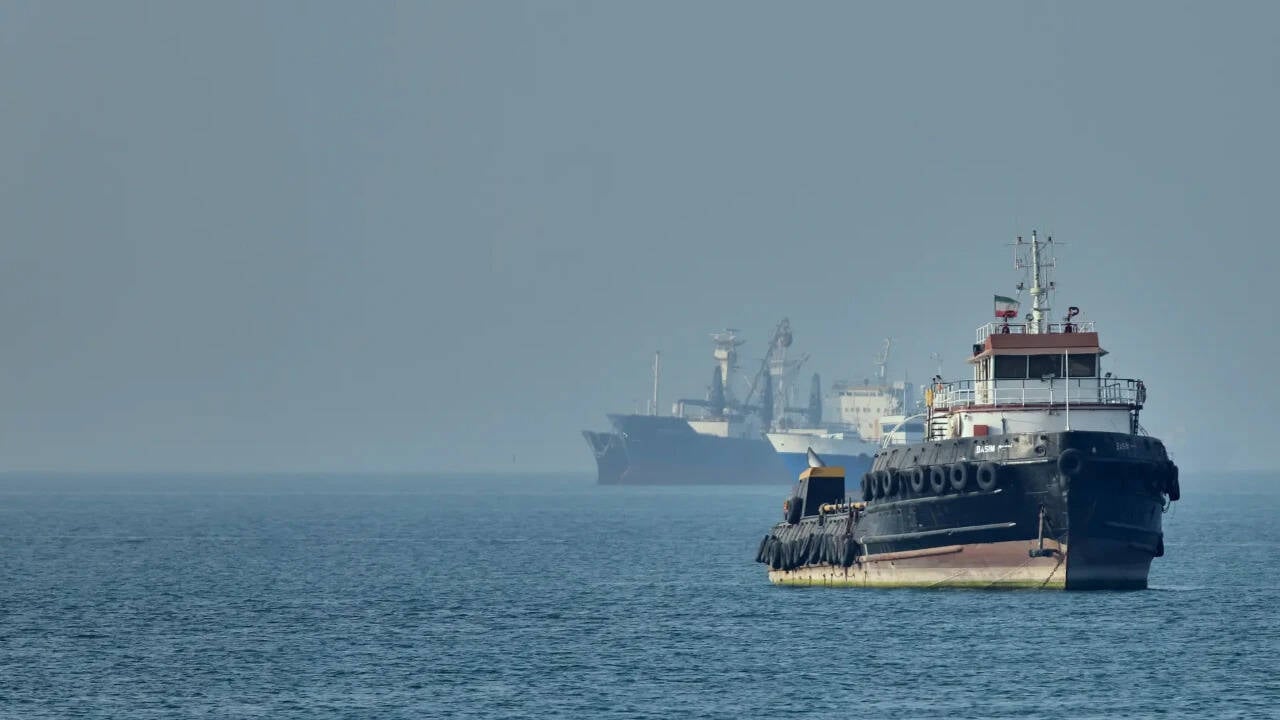
Global liquefied natural gas (LNG) supply could face a decline of up to 7 per cent this winter if disruptions in the Middle East persist, according to a report by the International Energy Agency (IEA). The agency warned that the market remains under significant pressure due to an unprecedented supply shock at the Strait of Hormuz.
Strait of Hormuz disruptions drive supply volatility
The IEA reported that LNG loadings from Qatar and the United Arab Emirates fell by 60 billion cubic metres (bcm) year-on-year between March and October 2026. This reduction contributed to a 5 per cent, or 20 bcm, drop in global LNG output, as new projects have only partially offset the losses from the Persian Gulf, ANI reported.
The agency outlined two primary scenarios for the winter period depending on the status of the waterway. If the Strait begins a progressive reopening in January 2027, global LNG supply could decline by around 9 bcm, or 3 per cent, year-on-year. However, if the Strait remains closed until the end of March 2027, the decline could be sharper, with global LNG supply falling by around 20 bcm, or 7 per cent, the, IEA said.
The IEA also noted that between November and March, global LNG supply could decline by 10–25 bcm year-on-year depending on the speed of recovery in the Strait. The agency cautioned that delays in ramping up production at new projects and unplanned outages could create additional downside risks to global supplies while Middle East disruptions continue.
The disruption of LNG flows through the Strait of Hormuz creates unprecedented uncertainty for the global LNG market ahead of the 2026/27 winter,
the report stated, adding that the supply shock looks set to keep imposing tighter market conditions during the northern hemisphere winter, even as supply from new liquefaction plants around the globe continues to grow.
While new and legacy projects outside the Persian Gulf are projected to add approximately 20 bcm of incremental supply during the winter period, the IEA stated this extra supply would remain insufficient to compensate for the lost volumes from Qatar and the United Arab Emirates.
European storage levels reach multi-year lows
Europe is entering the heating season with gas inventories at their lowest levels since 2013. As of 31 October, the European Union’s gas storage facilities were 75 per cent full, according to the IEA.

Recent data shows a rapid depletion of these reserves. ANSA reported that the EU lost nearly 1 per cent of its stocks in just three days, falling from 74.56 per cent to 73.75 per cent, which is equivalent to 835.1 TWh. Regional storage levels vary significantly:
- In Italy, stocks have dropped from 91 per cent to 90.08 per cent (183.24 TWh), which remains the highest figure among all European nations, ANSA reported.
- In Germany, stocks fell from 61.05 per cent to 60.25 per cent (149.02 TWh), ANSA reported.
The low reserves leave the continent particularly exposed
to cold spells. The IEA warned that if the Strait of Hormuz remains closed and Europe suffers colder-than-average weather conditions, gas storage levels could fall below 10 per cent of working capacity by the end of March 2027. The IEA noted that the market would be especially vulnerable because gas withdrawal rates tend to decline when storage facilities fall below 30 per cent of their working capacity.
The IEA’s Global Gas Security Review also estimated that the regional war could wipe 150 billion cubic metres (bcm) off global LNG supply between 2026 and 2030. This represents 15 per cent of the new liquefaction capacity expected to come online during that period.

Market prices react to US election outcomes
European natural gas prices have seen recent volatility. Benchmark futures at the Dutch Title Transfer Facility (TTF) fell by 2.2 per cent as of 9 a.m. on Thursday, reaching $96.87 (86.14 euros) per megawatt-hour, Oilprice reported. This decline followed optimism that US midterm election results could encourage diplomacy regarding the Iran war, Bloomberg reported.
While European prices dipped, LNG prices in Asia rose to $32 per million British thermal units (Btu) due to shipping restrictions in the Strait of Hormuz, ANSA reported. This equates to 97.24 euros per megawatt-hour.
Commodity analysts Warren Patterson and Ewa Manthey of ING noted that the outcome of the winter depends on Middle Eastern supply recovery. Where we come out the other side of winter is largely dependent on how much of a recovery we see in Persian Gulf LNG flows this winter, if any,
they said, adding that given the tighter market, weather is going to be even more important than usual through the winter,
Oilprice reported.