JetBlue Airways creditors have retained restructuring advisers as the carrier’s stock price hit an all-time low below $3 per share. Surging jet fuel costs, high debt obligations, and heavy short interest have intensified financial pressure on the airline ahead of its upcoming third-quarter earnings report.
Creditors Retain PJT Partners and Akin Gump Amid Record Low Shares
A group representing major creditors of JetBlue Airways has hired restructuring advisers PJT Partners along with law firm Akin Gump Strauss Hauer & Feld as the airline’s financial pressures mount. The creditor group includes holders of the carrier’s $2 billion in bonds due in 2031 and a $742 million first-lien loan.
The move follows a sharp drop in market valuation. Short interest in the stock has surged beyond 30% of its float ahead of the airline’s scheduled third-quarter earnings announcement.

Surging Jet Fuel Expenses and Heavy Debt Obligations Pressurize Cash Flow
Operational challenges have collided with a severe energy price shock. JetBlue abandoned forward contracts for jet fuel, leaving the carrier directly exposed to market volatility. Jet fuel prices have risen approximately 120% since October 2025.
The fuel price spike is estimated to add approximately $2.5 billion in additional costs for JetBlue in 2026. This financial burden compounds a balance sheet already heavily burdened by about $8.5 billion in debt and finance lease obligations, excluding operating lease liabilities. The airline lost $566 million during the first half of 2026, even as quarterly revenue climbed 14.5% to $2.7 billion.
| Debt Repayment Schedule | Amount Due |
|---|---|
| Remainder of 2026 | $236 million |
| 2027 | $478 million |
| 2028 | $582 million |
| 2029 | $1.835 billion |
The carrier has negative operating and net margins. Multiple Wall Street research firms have adjusted their stances ahead of the Q3 earnings release, reflecting a broad reset of expectations for the carrier. Barclays lowered its price objective from $7.00 to $5.00 with an equal weight rating, TD Cowen moved its target from $6.00 to $5.00 with a hold rating, and Susquehanna trimmed its target from $6.00 to $4.00 while maintaining a neutral rating. Goldman Sachs maintains a sell rating with a $3.50 target, whereas Citigroup shifted its view from sell to neutral.
According to market data, JetBlue operates as a passenger carrier offering scheduled flights across the United States, Latin America, the Caribbean, and select European and Canadian destinations, catering to both vacation and corporate flyers via a hub system anchored by key U.S. air hubs like Boston, New York, Orlando, and Fort Lauderdale. Even while managing a debt load near $9 billion, the carrier disclosed possessing approximately $2.2 billion in liquid assets—comprising unrestricted cash, equivalents, and investments—as of June 2026, accompanied by an untouched credit line of $600 million.
United Airlines CEO Asked About Acquisition While Turnaround Strategy Continues
Market speculation regarding a potential takeover by a larger carrier has circulated due to JetBlue’s valuable assets, including New York airport slots, Boston operations, and a significant presence in Fort Lauderdale. However, United Airlines CEO Scott Kirby was asked whether he might buy the airline on October 21 but declined to signal any change in the carrier’s position.
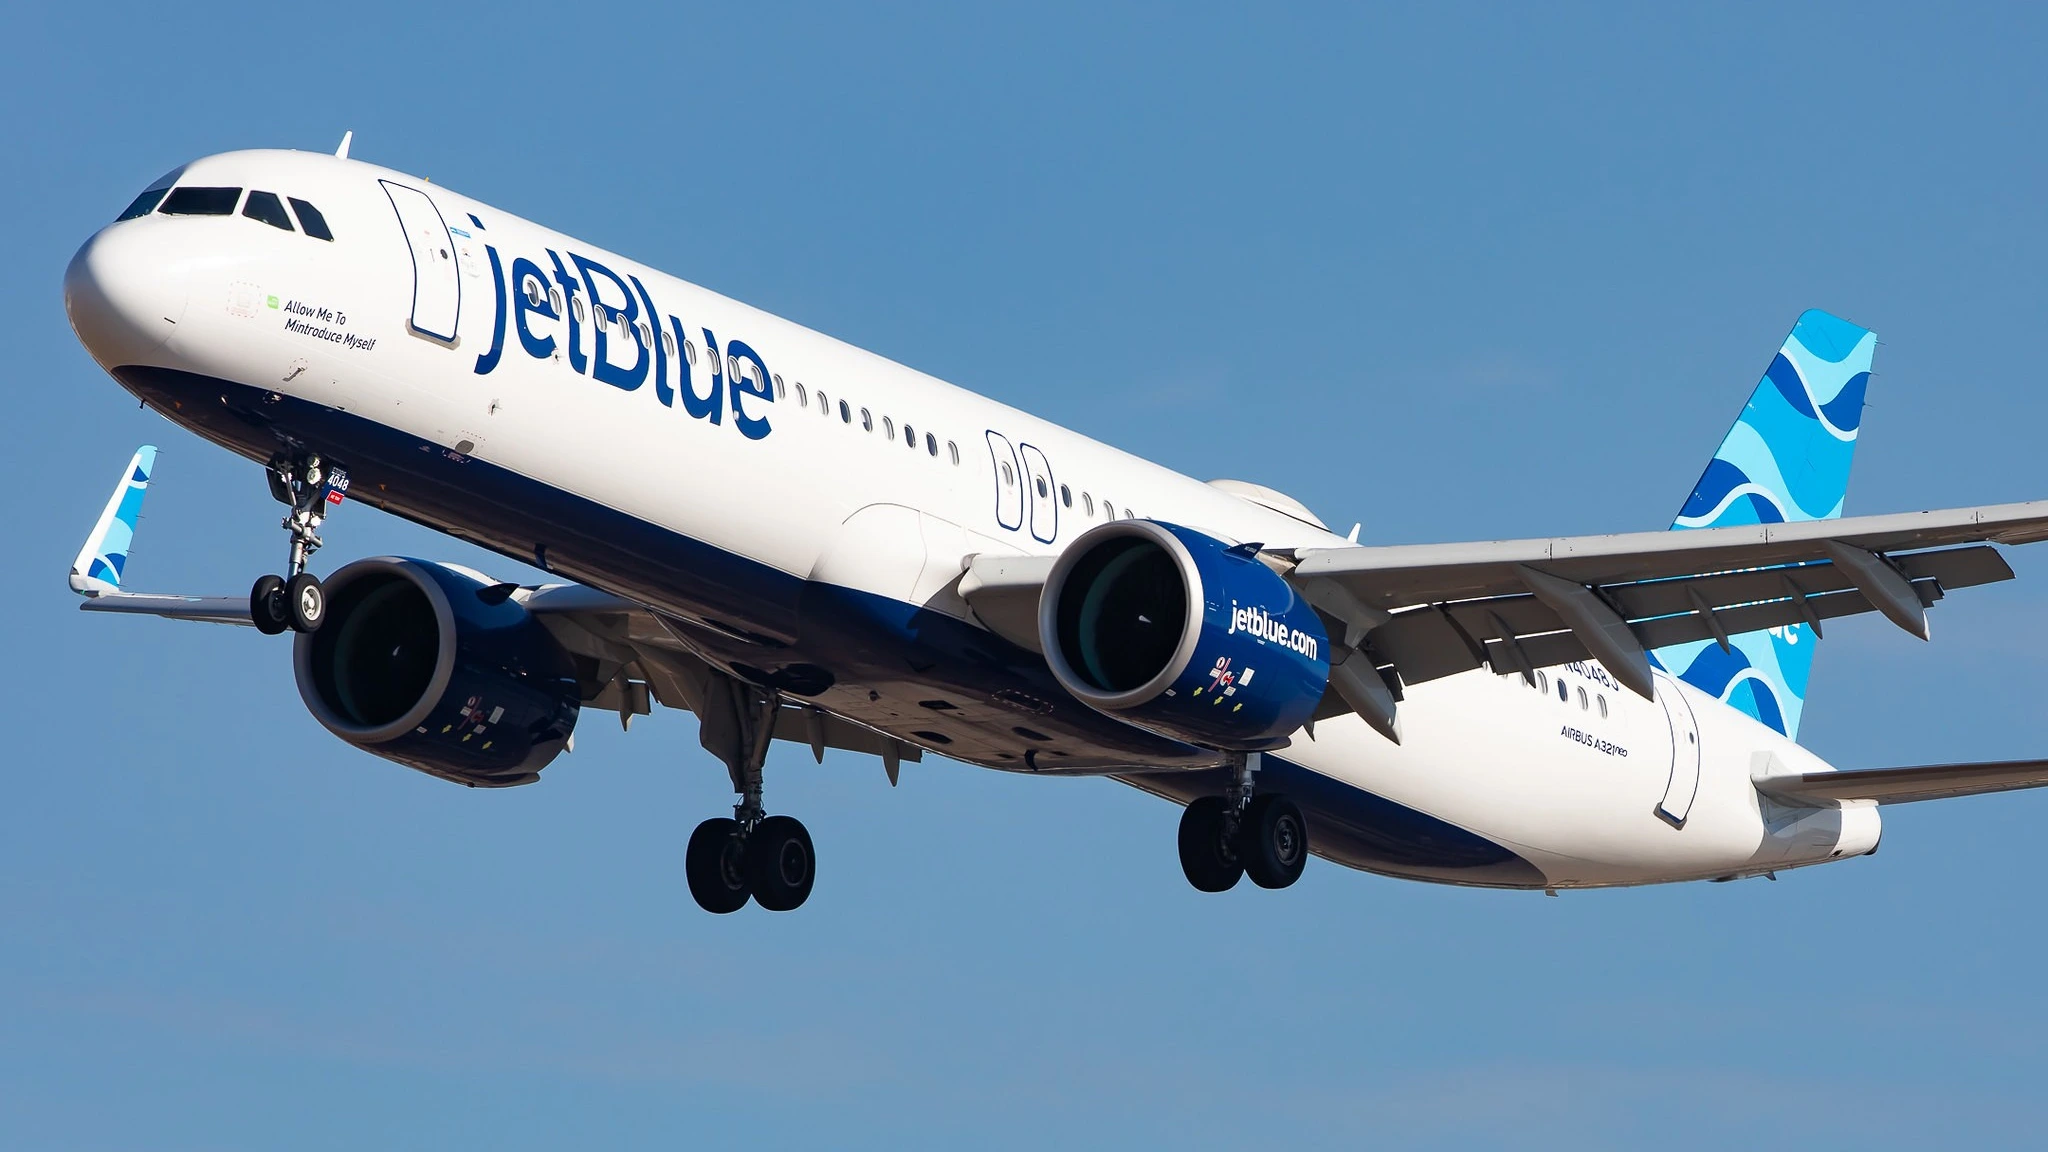
JetBlue remains confident in its JetForward strategy and the progress being made toward returning to sustained profitability.
JetBlue Airways, via Reuters
Management is attempting to survive the downturn by preserving cash. The carrier has deferred 44 Airbus A321neo deliveries to 2030 and beyond. As lenders and investors await the third-quarter financial results, the airline maintains that its operational overhaul remains the primary path toward financial recovery.