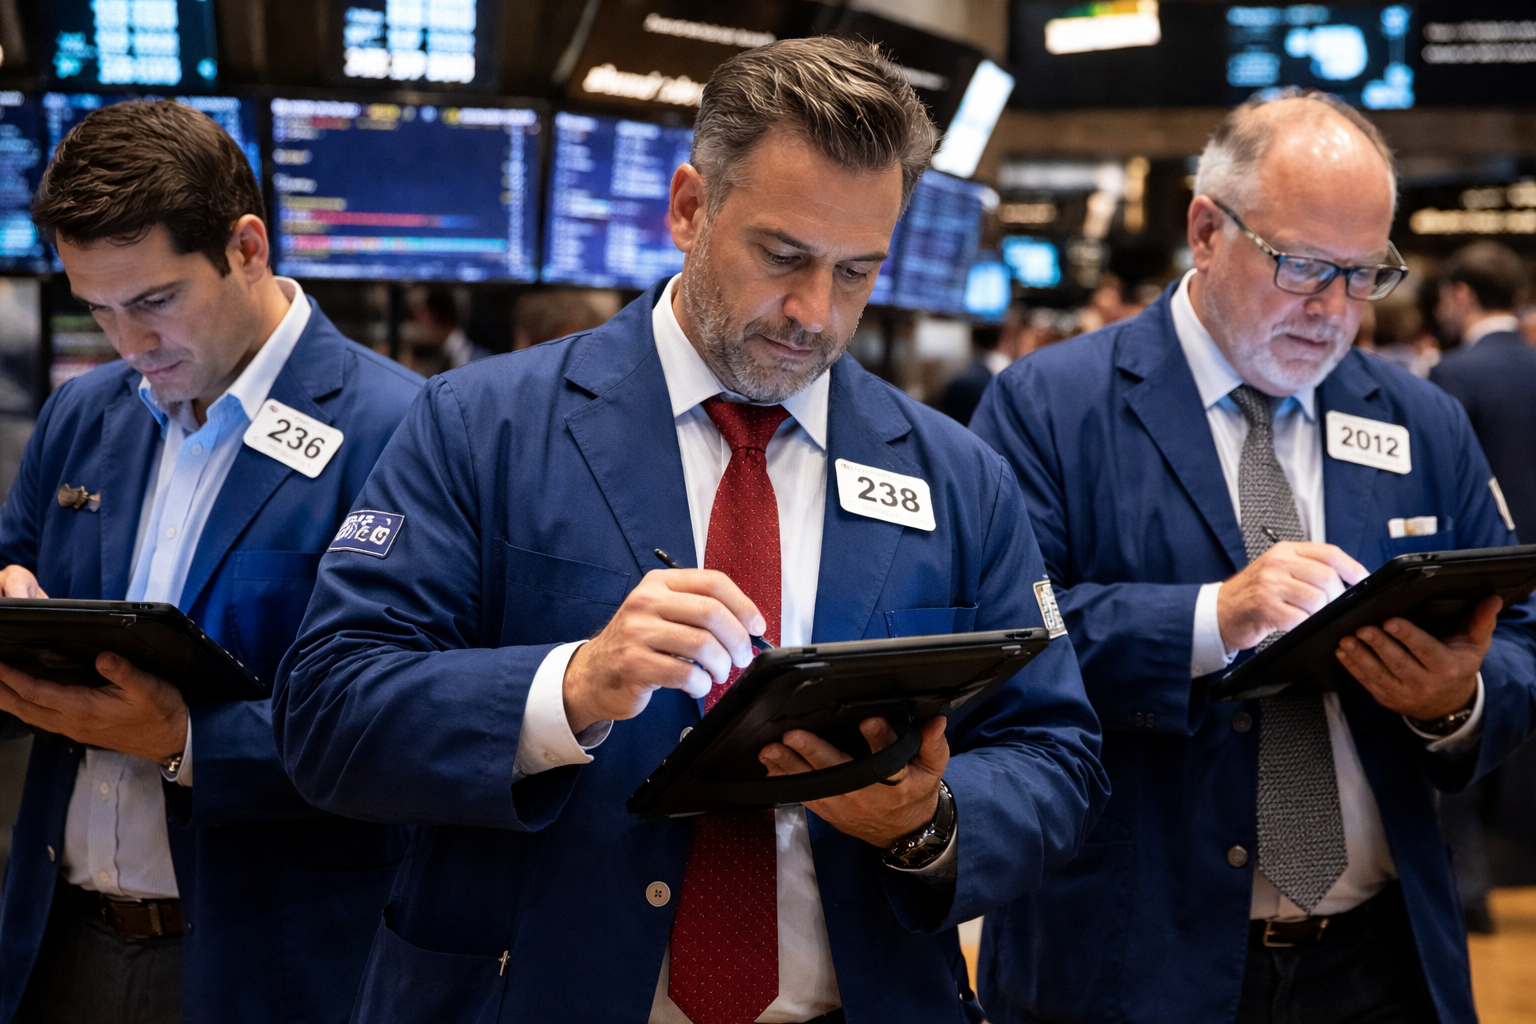
Global stock markets absorbed broad declines on Thursday, October 22, 2026, driven by a sharp tech sell-off and a surge in oil prices above 113 dollars per barrel. In the United States, the tech-heavy Nasdaq index dropped 2.6 percent, while analysts pointed to investor anxiety over artificial intelligence infrastructure costs.
Financial markets across Europe, Asia, and North America flashed red as investors reassessed the massive capital flowing into artificial intelligence infrastructure. Major technology equities faced steep reversals, with prominent software and semiconductor firms retreating on Wall Street and European exchanges. The Stoxx Europe 600 index closed down 0.94 percent, while Frankfurt fell 1 percent and Paris slid 1.6 percent, according to reporting by E24. On Wall Street, the broad S&P 500 index lost 1.21 percent, and the Nasdaq finished down 2.60 percent, though the Dow Jones managed a fractional gain of 0.02 percent.

Meta and Tesla Earnings Trigger Tech Sector Reversals
The downturn followed third-quarter earnings reports from prominent technology corporations. Meta Platforms reported revenues of 64,6 milliarder dollar, a 26 percent increase from the previous year, alongside a per-share result of 2,83 dollar. Despite topping analyst expectations, Meta shares fell 7 percent, erasing over 1200 milliarder kroner in market capitalization. The company also reported a negative free cash flow driven by extensive infrastructure outlays, while its operating results absorbed separate costs, as detailed by Invezz.
Electric vehicle manufacturer Tesla saw its shares slide 3 percent after reporting stable overall revenues alongside declining automotive receipts. Tesla also reduced its capital expenditure projection for the year to roughly 20 milliarder dollar down from more than 25 milliarder dollar. Semiconductor equipment provider Lam Research announced quarterly revenues, yet saw its shares drop about 8.5 percent in pre-market trading after issuing a projected revenue outlook for the upcoming quarter, as reported by Invezz.
Market Observers Debate Artificial Intelligence Infrastructure Spending
Market participants increasingly scrutinized whether astronomical spending on artificial intelligence will yield proportional financial returns. Robert Næss, investment director at Nordea Wealth Management, noted that the market is experiencing an unprecedented sector rotation rather than an outright exit from equities, telling E24 that investors are moving capital away from giants like Nvidia, Amazon, and Meta. Næss highlighted growing apprehension that anticipated revenue growth from AI buildouts may fall short of projections because infrastructure is not being deployed as rapidly as previously assumed.
That sentiment was echoed internationally. Santiago Mateo, head of equities at CaixaBank AM, told Bloomberg in coverage cited by E24 that markets remain willing to reward heavy artificial intelligence investments but are becoming vastly more demanding regarding returns and revenue generation. Similarly, Ben Barringer, head of technology research at Quilter Cheviot, noted to The Wall Street Journal in reporting covered by Invezz that lofty expectations make it increasingly difficult for technology firms to satisfy investor demands.

Sector Rotation and Oil Price Pressures Shape Investor Sentiment
As technology shares retreated, capital flowed toward safer assets, driving down long-term government bond yields. The yield on ten-year U.S. Treasury bonds fell by more than 12 basis points through the day to around 4.96 percent, according to DNB. Roger Berntsen, an analyst at Nordnet, argued that the turbulence reflects classic sector rotation rather than systemic panic. In comments to Nettavisen, Berntsen emphasized that ordinary fund savers holding diversified global portfolios are better insulated against single-stock shocks than focused investors.
Adding to the economic headwinds, Brent crude oil prices climbed past 113 dollars per barrel by the Wall Street close, marking levels not seen since mid-May. Concerns over supply disruptions following Middle East conflicts further elevated inflation expectations and bond yields. Joachim Bernhardsen, chief strategist at Nordea, offered a more cautious view in a weekly report noted by Nettavisen, stating that market panic was dominating sentiment as participants question whether monumental AI investments will generate sufficient future income.
Amid these developments, global equity markets also processed broader macroeconomic data, including the eurozone purchasing managers’ indices, which showed slight resilience before the latest round of energy price pressures took effect. Tim Waterer, chief market analyst at KCM Trade, observed that investors have proven particularly difficult to satisfy in the current trading environment. Meanwhile, Stifel analyst Brian Chin remarked that favorable conditions within the memory chip market could endure for another two to three years, even if valuations for suppliers like Micron face near-term headwinds. Concurrently, analysis from Gartner highlighted that the global data center sector faces massive capital requirements to fund ongoing artificial intelligence deployments.