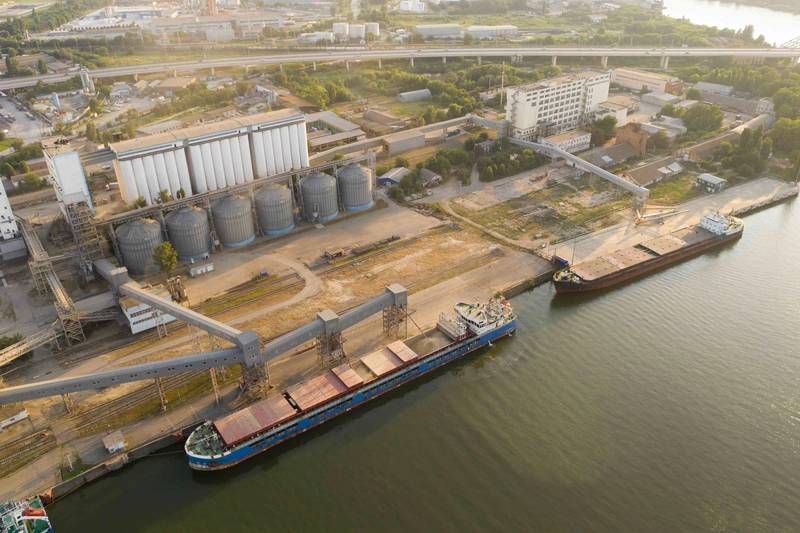
Russian grain exporters are exploring new supply routes through China and expanding Baltic capacity as Ukrainian drone strikes paralyze Azov and Black Sea terminals.
Seaborne grain shipments from Russia’s southern ports have collapsed following a systematic campaign of Ukrainian drone strikes in the Sea of Azov and Black Sea. Over the course of a week from July 6 to July 12, 2026, Ukrainian unmanned systems struck 90 Russian vessels before reaching a total of 105 ships targeted within eight days. The operations paralyzed Azov Sea ports and heavily disrupted terminals in Novorossiysk and Tuapse, prompting Moscow to temporarily suspend navigation through the Don–Azov Canal and halt applications for passage through the Kerch Strait.
The disruption has crippled the country’s primary agricultural export arteries. According to data from Ukraine’s Foreign Intelligence Service, the second 10-day period of September saw wheat shipments via the Black Sea drop sharply to 347,000 metric tons, falling from the 1.3 million tons recorded during the corresponding timeframe in 2025. Shipments specifically through Novorossiysk fell from 696,000 tons to 72,500 tons year-over-year. ProZerno analytical firm head Vladimir Petrichenko calculated that total export potential could drop from a targeted 59 million tons to 39 million tons out of an overall harvest of roughly 140 million tons, leaving an estimated 20 million tons of grain without buyers.
Baltic Sea Ports Rush to Handle Grain Rerouting
With southern terminals choked off, exporters have rushed to reroute shipments through Baltic Sea ports, which handled only about 2% of Russian grain exports last season but possessed significant spare capacity. Industry operators are actively converting fertilizer and coal terminals to handle grain as volumes surge. Russia’s Baltic ports boosted their annual capacity to handle grain exports to 23.5 million metric tons in October, up from 8.6 million tons in July, according to a senior Russian Railways executive.
Deputy Agriculture Minister Maxim Borovoi estimated at an October conference in Moscow that Russian Baltic ports could handle as much grain this October as they did during the entire previous season. Analysts estimated that the proportion of Russian wheat exports shipped through Baltic ports reached 60% in September. Dmitry Rylko, head of the Ikar consultancy, praised the rapid expansion, noting that the Baltic region managed to ramp up volumes quickly despite the sharp decline in southern shipments.
Despite the rapid pivot, analysts warn that the Baltic corridor cannot fully make up for the losses in the south. Rusagrotrans railway carrier analysts pointed out that further progress depends heavily on existing railway capacity and the availability of rail cars. Ksenia Bolomatova, executive director of Russia’s Union of Grain Exporters and Producers, noted that while the Baltic Sea allows supplies to reach customers in the Middle East, Türkiye, and North Africa, reaching distant Asian markets such as Indonesia from those northern locations remains problematic due to high logistics costs.
Overland Corridors to China and Arctic Test Routes
To bypass maritime bottlenecks altogether, Russian grain exporters are exploring new supply routes through China and testing northern transshipment options. Rising from 2.3 million tons in 2024 to 5.8 million in 2025, volumes moving through the New Land Grain Corridor are projected to hit approximately 9 million tons during the current year. However, Ukrainian intelligence reported that this overland trade faces strict limitations, including rail and terminal capacity constraints, tariffs, Chinese quotas, and phytosanitary requirements.
Moscow has also tested a northern shipping route through Murmansk. Russian Railways approved an initial shipment of 40,000 tons originating from Stavropol Krai. Transporting grain from the country’s main producing regions to the Arctic port adds an estimated $18 to $25 per ton in logistics costs, complicating commercial viability.
Excess Stocks Cut Southern Russian Grain Prices
The inability to fully replace Black Sea export capacity has triggered severe domestic consequences. The sharp drop in foreign shipments led to a substantial build-up of excess stocks inside the country. Over-supply has already cut grain prices in southern Russia roughly in half, plunging values to between 4,000 and 5,000 rubles per ton. ProZerno analysts estimate that carryover stocks could reach 34.8 million tons by the end of the year.
Regional geopolitical hurdles further complicate the Baltic alternative. Sovecon estimated that Russian wheat exports through Baltic ports reached 1.3 million tons in September, with 400,000 tons moving through ports in Latvia and Lithuania. Both European Union and NATO member states have declared intentions to end shipments of Russian grain, with Latvia introducing a planned 300% tariff. Industry sources noted that while shipments are currently proceeding, Latvian authorities have implemented additional checks to verify whether grain originates from Russian-controlled regions of Ukraine, causing operational delays.