Four-hour battery storage systems are now more cost-effective than new open-cycle gas turbines in all 43 global markets modeled by Wood Mackenzie. As utility-scale solar and wind integration accelerates, the shift is effectively closing the economic case for new gas peaking plants, despite regional variations in trade policy and supply chain constraints.
The Shift in Global Peaking Economics
The latest levelized cost of electricity (LCOE) report from Wood Mackenzie confirms a structural turning point for power systems. In every market analyzed, the economics of four-hour battery storage have overtaken gas-fired peaking capacity. Depending on the application of state-level carbon pricing, 4-hour battery storage systems scheduled for a 2026 commercial operation date in the United States are 65% to 75% cheaper than new open-cycle gas turbine peakers.

“This economic shift is decisive and widening.”
Ahmed Jameel Abdullah, principal analyst at Wood Mackenzie
“It is about storage and solar together redefining what the economics of a power system look like. From Latin America to Asia Pacific, the combination of falling storage costs and world-class renewable resources is closing off the economic case for new gas peaking capacity globally.”
Ahmed Jameel Abdullah, principal analyst at Wood Mackenzie
China Leads Global Grid-Scale Storage Cost Reductions
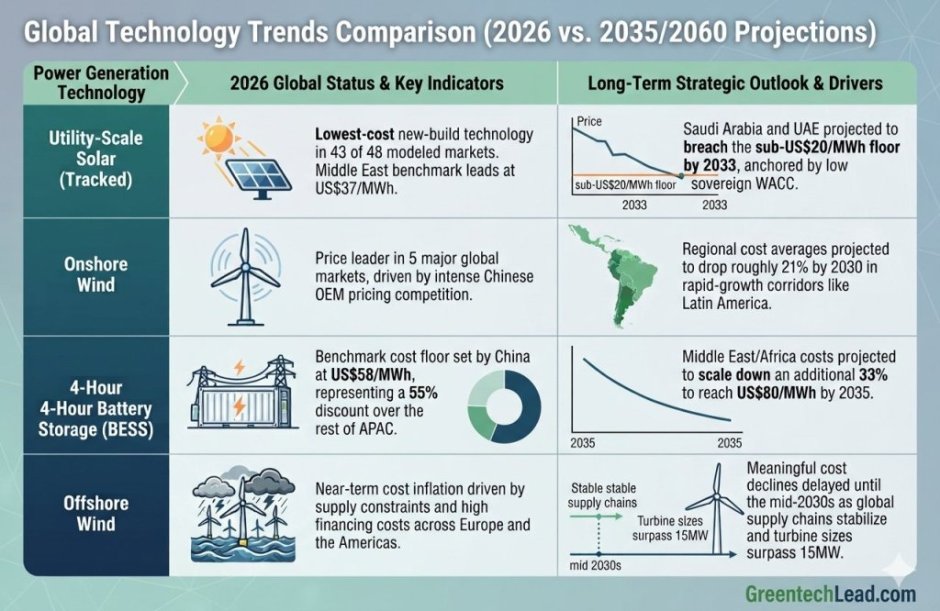
While the trend is global, the speed of adoption varies significantly by region. China remains the global benchmark for grid-scale storage costs, with LCOE levels more than 55 percent lower than the rest of the Asia Pacific average of $134/MWh. This advantage is largely attributed to integrated domestic supply chains and manufacturing at scale. In the Middle East and Africa, utility-scale solar already leads at $37/MWh, while four-hour storage is forecast to fall 33 percent to $80/MWh by 2035, displacing gas peaking across every gas market in that region.
Tariffs and Data Center Load Pressure North American Costs
Following a 10% rebound in cell prices, turnkey battery storage capex experienced a slight 2% increase in 2026, though expectations point toward a 12% cost reduction by 2031. Near-term solar costs in the region are under pressure from tariffs, anti-dumping and countervailing duty actions, and new import restrictions. Investment in gas generation capacity is entering a supply deficit cycle through the late 2030s, driven by data center load growth. Because of these factors, thermal capital costs remain high, with gas turbine prices anticipated to climb to $600/kW by the close of 2027, marking a 195% rise since 2019.
Long-term Trajectories for Renewables
However, over the long term, new battery chemistries, hardware commoditization, and domestic supply chain expansion are expected to drive storage LCOE down 10% by 2060. Project decisions must ultimately consider charging costs, grid access, utilization, financing, and the specific hours when electricity is needed, as the Wood Mackenzie findings provide a technology cost benchmark rather than a total system solution.