US stocks closed higher on October 2 as softer-than-expected September jobs data eased concerns about an imminent Federal Reserve rate hike, with the S&P 500 and Nasdaq Composite posting gains amid cautious optimism about economic stability.
The S&P 500 Index rose 0.7% to 7,722.72, climbing 56.27 points, while the Nasdaq Composite added 1.19% to 27,190.86, driven by lower expectations for a rate increase following the Labour Department’s report of 29,000 new jobs in September, far below the 90,000 median estimate. The Russell 2000 Index gained 0.9%, marking its biggest daily rise in a month, as small-cap stocks outperformed. The Labour Department also revised prior months’ job counts sharply lower, contributing to the downward adjustment in rate hike expectations.
Market Reaction to Softer Jobs Data
This shift bolstered investor sentiment, with mega-cap stocks like Nvidia and Tesla contributing to the S&P 500’s advance. Small-cap stocks, including the Russell 2000, outperformed as rate-sensitive sectors benefited from the revised outlook. The S&P 500 real estate index rose 0.4%, reflecting heightened demand for rate-sensitive assets.
Today’s news was OK insofar as it means the economy isn’t roaring,
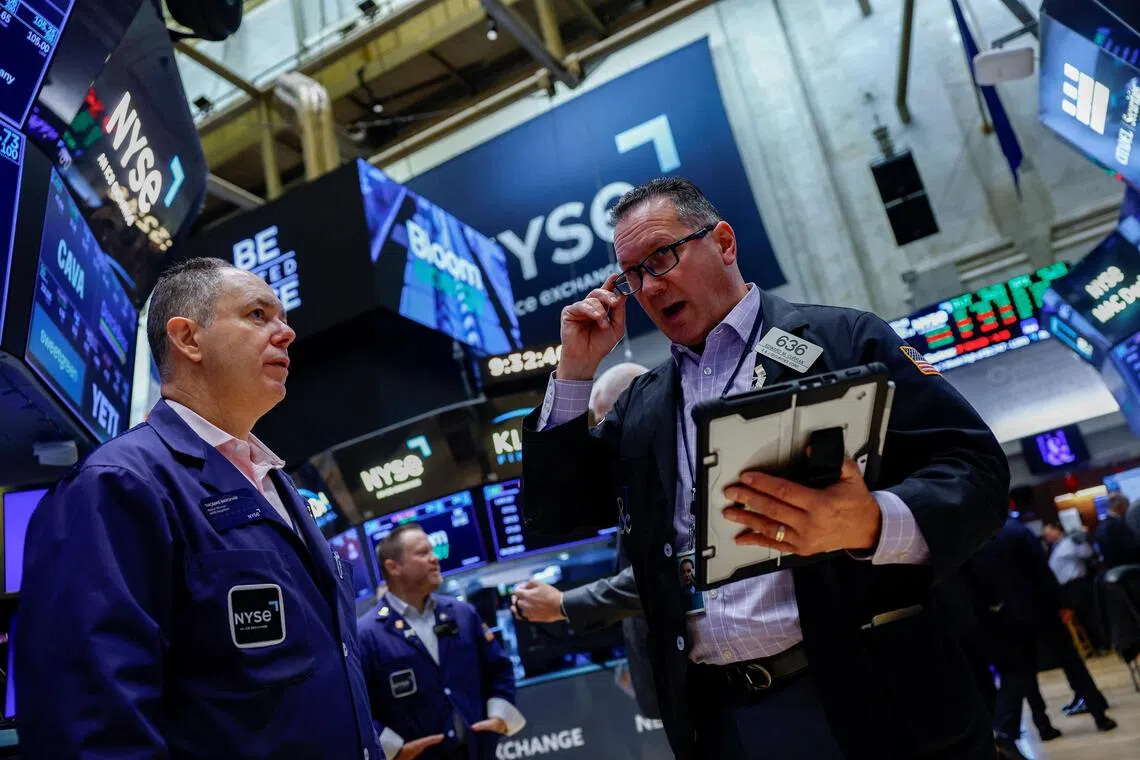
said Robert Bernstone, head of trading at SummitTX Capital, according to the Straitstimes. But how good is that? Yes, it’s fine insofar as it takes the short-term rate hike off, but there is a concern over the economy, there is a concern over inflation, so cautious optimism is kind of where people are.
The Labour Department’s data also highlighted broader economic uncertainties, with the S&P 500 real estate index gaining 0.4% and the tech sector facing mixed performance. The Nasdaq secured a 0.45% weekly rise, while the Dow fell 1.26%.
Economic Outlook and Rate Hike Expectations
Investors remain wary of potential market volatility, with Bernstone noting a potential squeeze into the end of the year
due to a “hated rally” dynamic. The Federal Reserve’s stance on rate hikes remains a focal point, with policymakers cautioning against further increases amid resilient economic activity and slower inflation. The S&P 500's weekly performance highlighted the market's sensitivity to macroeconomic signals, with investors balancing optimism about rate cuts against lingering concerns about inflation and global economic stability.

The Labour Department’s report, which also revised prior months’ data lower, reduced the probability of a Fed rate hike to 22.7% by the end of October, according to CME FedWatch.
Broader Implications for the Financial Sector
The S&P 500's weekly performance highlighted the market's sensitivity to macroeconomic signals, with investors balancing optimism about rate cuts against lingering concerns about inflation and global economic stability. The S&P 500 ETF components also reflected heightened market activity, with the iShares Core S&P 500 ETF showing increased trading volume.
The Labour Department’s report, which revised prior months’ job counts sharply lower, contributed to the revised outlook for Fed policy.