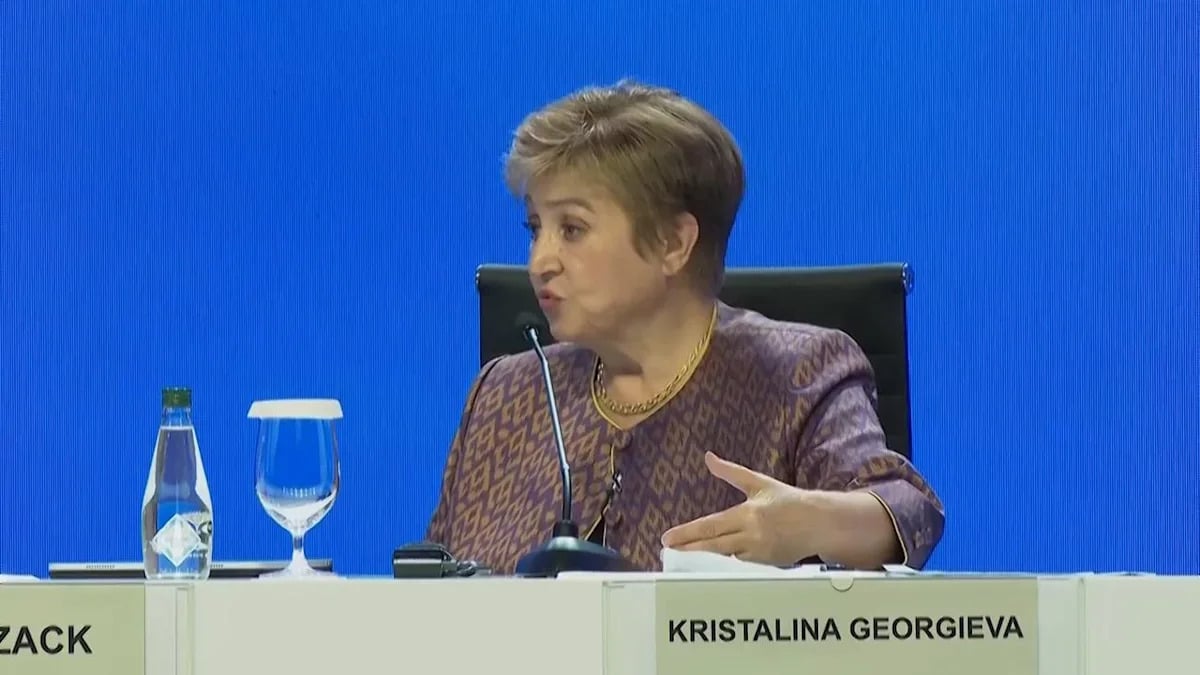
International Monetary Fund Managing Director Kristalina Georgieva urged the United States and other wealthy nations to urgently tackle mounting global debt during meetings in Bangkok, warning that economic growth alone cannot close deficits exceeding forty trillion dollars.
Global economic pressures are mounting as high interest rates and swelling national liabilities strain both advanced economies and developing nations. During the autumn meetings of the International Monetary Fund and the World Bank Group in Bangkok, IMF Managing Director Kristalina Georgieva addressed the financial system strains caused by climbing debt burdens.
United States Debt Deficit Realities and Market Disruption
Georgieva noted that Treasury Secretary Scott Bessent and other U.S. leaders acknowledge that federal deficits and national obligations are too high. Yet, officials face difficult mathematics regarding the U.S. national debt, which now exceeds $40 trillion. Financial markets face immediate disruption from rising bond yields as investors demand larger premiums to cover growing risks.
We believe that growth, of course, helps, but it cannot deliver fast enough the necessary adjustments.
Kristalina Georgieva, IMF Managing Director
The IMF chief emphasized that there are no quick fixes for structural imbalances. There is no magic,
Georgieva said, adding that leaders must actively pursue fiscal consolidation by reducing deficits and tightening budgets.
Fiscal Risks and Global Spillover Effects
Pandemic-era spending, subsequent heavy government outlays, and soaring energy costs linked to the Iran war have pushed global interest rates to multidecade highs. These conditions have intensified the vulnerabilities of low-income countries.

Fiscal risks are rising, and a proper reaction is largely absent in many countries.
Rodrigo Valdes, Director of the IMF’s Fiscal Affairs Department
Valdes warned that fiscal indiscipline in major advanced economies does not remain contained within domestic borders. Instead, financial instability travels outward, affecting the entire global economy. According to the latest Fiscal Monitor published by the International Monetary Fund, interest payments among the world’s poorest nations have surged to historic highs relative to government revenue. At the same time, declining international aid has created financing gaps that many developing governments cannot bridge.
The Burden on the Global South and Developing Nations
Developing countries find themselves trapped between servicing external obligations and funding domestic social programs for vulnerable populations.
The Global South is paying the price for rising interest rates in wealthier countries.
Ed Miliband, U.K. Foreign Secretary
Speaking on the sidelines of the summit, Miliband called for a new deal on debt to support countries to repay over longer time horizons and refinancing with better rates to give developing countries fiscal space.
Alexander De Croo, administrator of the United Nations Development Programme and former Belgian prime minister, pointed out that the median developing nation pays three times as much in interest as developed countries. On average, nearly 10% of government spending goes toward debt repayments. Combined with high fertilizer prices, fuel costs, and the effects of the El Niño weather phenomenon, low-income nations possess little room to recover.
I mean, we don’t see really a light at the end of the tunnel.
Alexander De Croo, UNDP Administrator
Employment Initiatives and Financial Security Measures
Beyond debt restructuring, international organizations are working to address broader macroeconomic stability and employment challenges. Over the next decade, more than 1.2 billion young people will enter the global workforce, while current projections indicate only 400 million net new jobs will be created, a shortfall compounded by artificial intelligence threatening traditional professions.
To counter these employment gaps, the UNDP launched its Jobs for Prosperity
initiative to connect governments, development banks, and private enterprises. The program aims to boost investment in food processing, healthcare, and tourism by improving governance and building pipelines of investible projects.
Meanwhile, institutional leaders also targeted financial crime. The International Monetary Fund, Bank of Thailand, and World Bank Group unveiled the Bangkok Blueprint to combat online scams, financial fraud, and cybercrime.